October 2026 - Monthly Market Update
/Monthly Update || October 2026
“Given what’s going on in the economy and the capital spending boom and the war for capital, if anything, [bond yields seem] a little low.”
Opening Remarks
Greetings from Ikigai Asset Management¹. We welcome the opportunity to bring to you our ninety-seventh Monthly Update and hope these are helpful in better understanding some of what we’re doing and what we’re seeing. We have the privilege of deploying capital on behalf of our investors into new technologies that have tremendous potential to make the world a better place and create trillions of dollars of value in the process.
We believe, in some cases, that we are obligated to be shepherds of some of these technologies – to do our little part to push ideas towards fulfilling their potential. We strive to be an objective, reasonable, well-intentioned voice of truth amongst a chorus of biased, fallacious, pernicious opportunists. It’s an honor that we take seriously.
To that end, a lot happened in the month of September on a number of fronts. I’d say the biggest overall occurrence in September was the “AI slowdown” situation. We’ll cover that in detail later.
The second biggest occurrence would be the rebound in Gulf crude exports to ~70-80% of pre-war levels by the end of September, and the knock-on effect of a presumed loss of bargaining power from Iran.
Despite increased Gulf exports by month-end, crude prices stayed high, with front-month Brent hovering around $100/bbl. Retail diesel prices hit $6.50/gal, the highest ever.
September also brought us the first Fed rate hike since July 2023. The US10Y was up nearly a half percent in Sept. US30Y hit highest level since June 2002. Fed Funds Futures market is pricing in 1.3 hikes in the last two FOMC meetings of 2026…. Stocks took it in stride. QQQ +3% in Sept, just underneath prior ATH. Gold -7% on the month.
Clarity Act failed. Crypto took it in stride. BTC/ETH/SOL +6%/9%/15% on the month. ZEC was +69%. NEAR was +178%.
We are now one month out from mid-term elections. Trump’s approval ratings are at an all-time low-
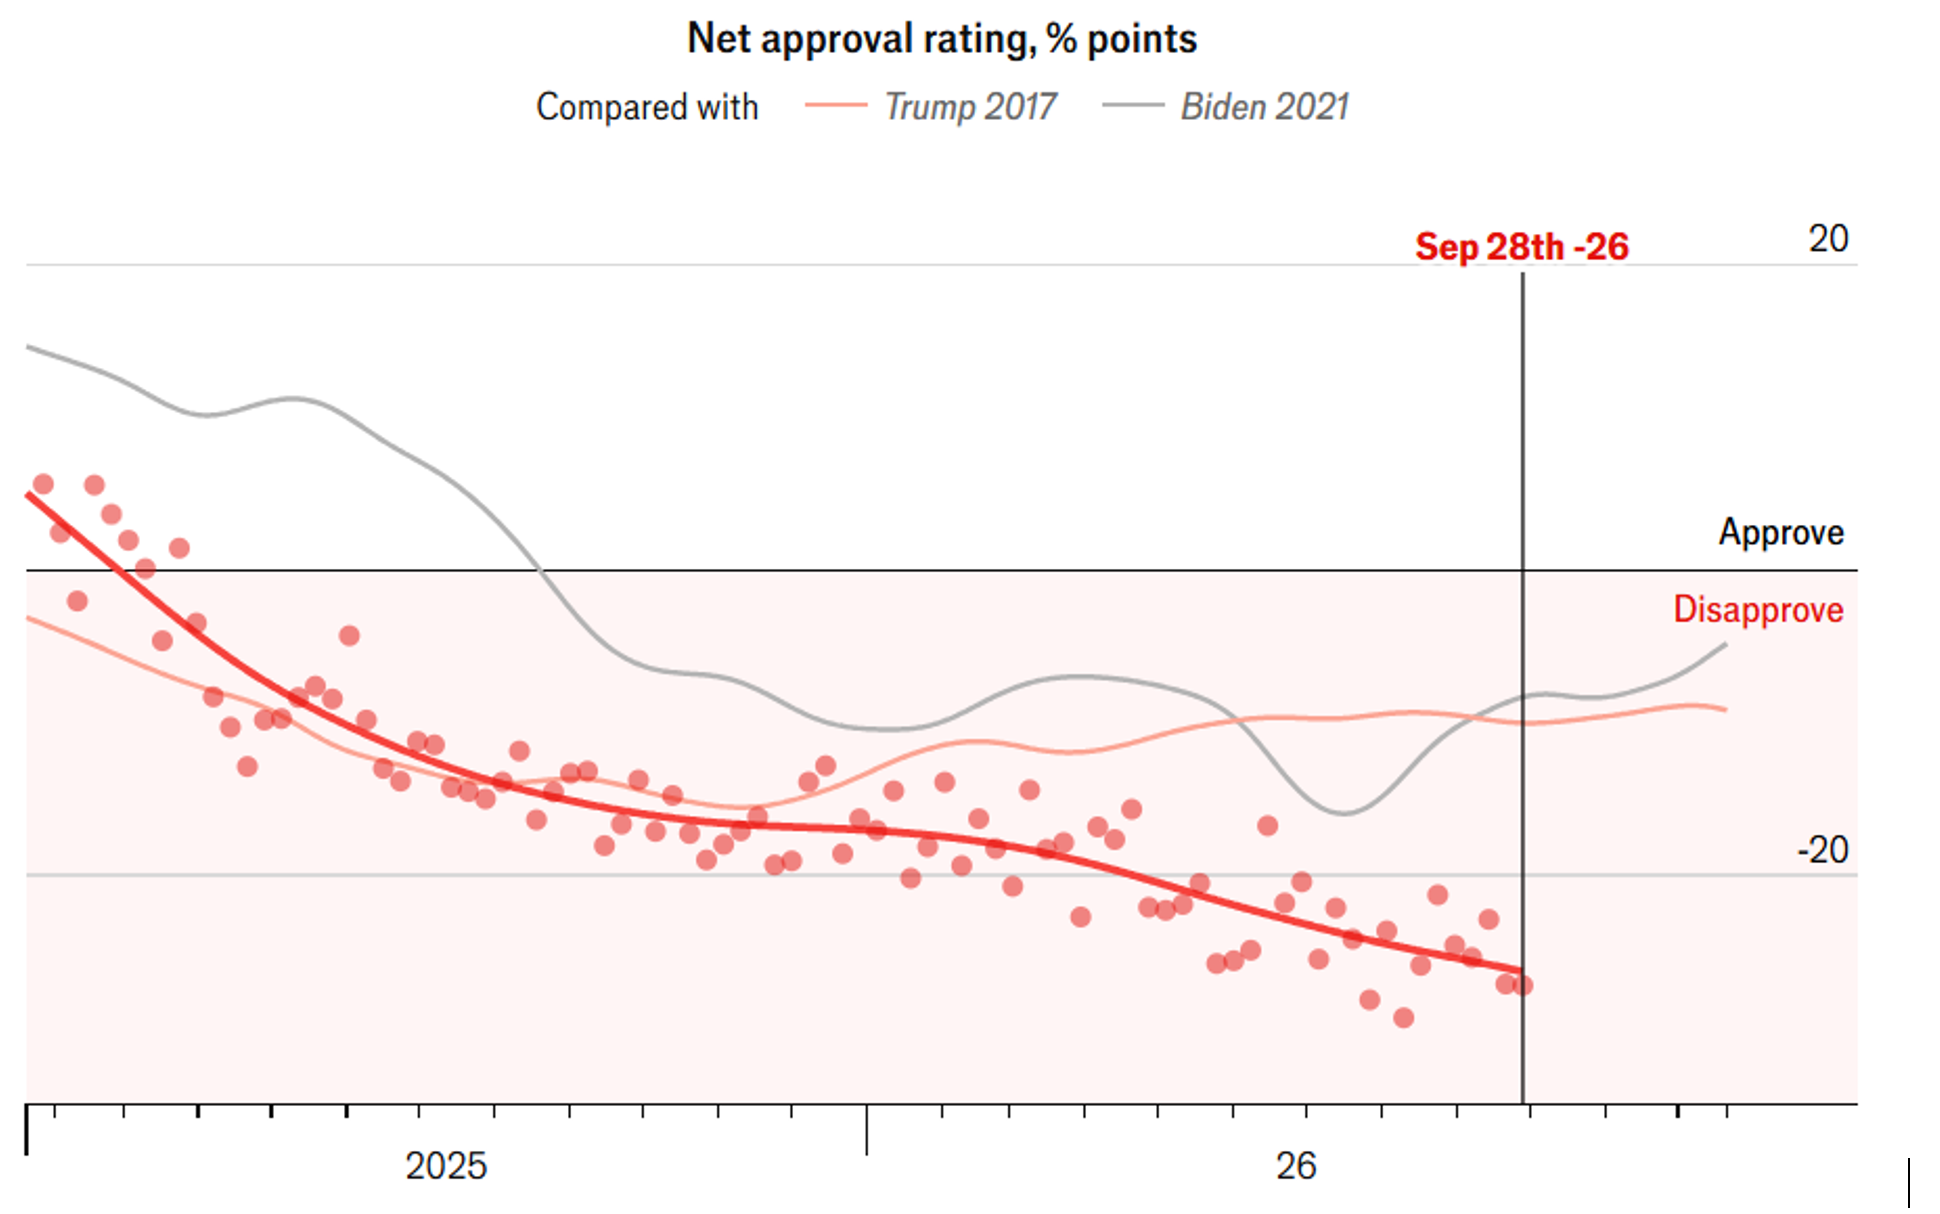
Source: The Economist. As of 9/28/26.
Democratic House is trading at 91c on Kalshi-
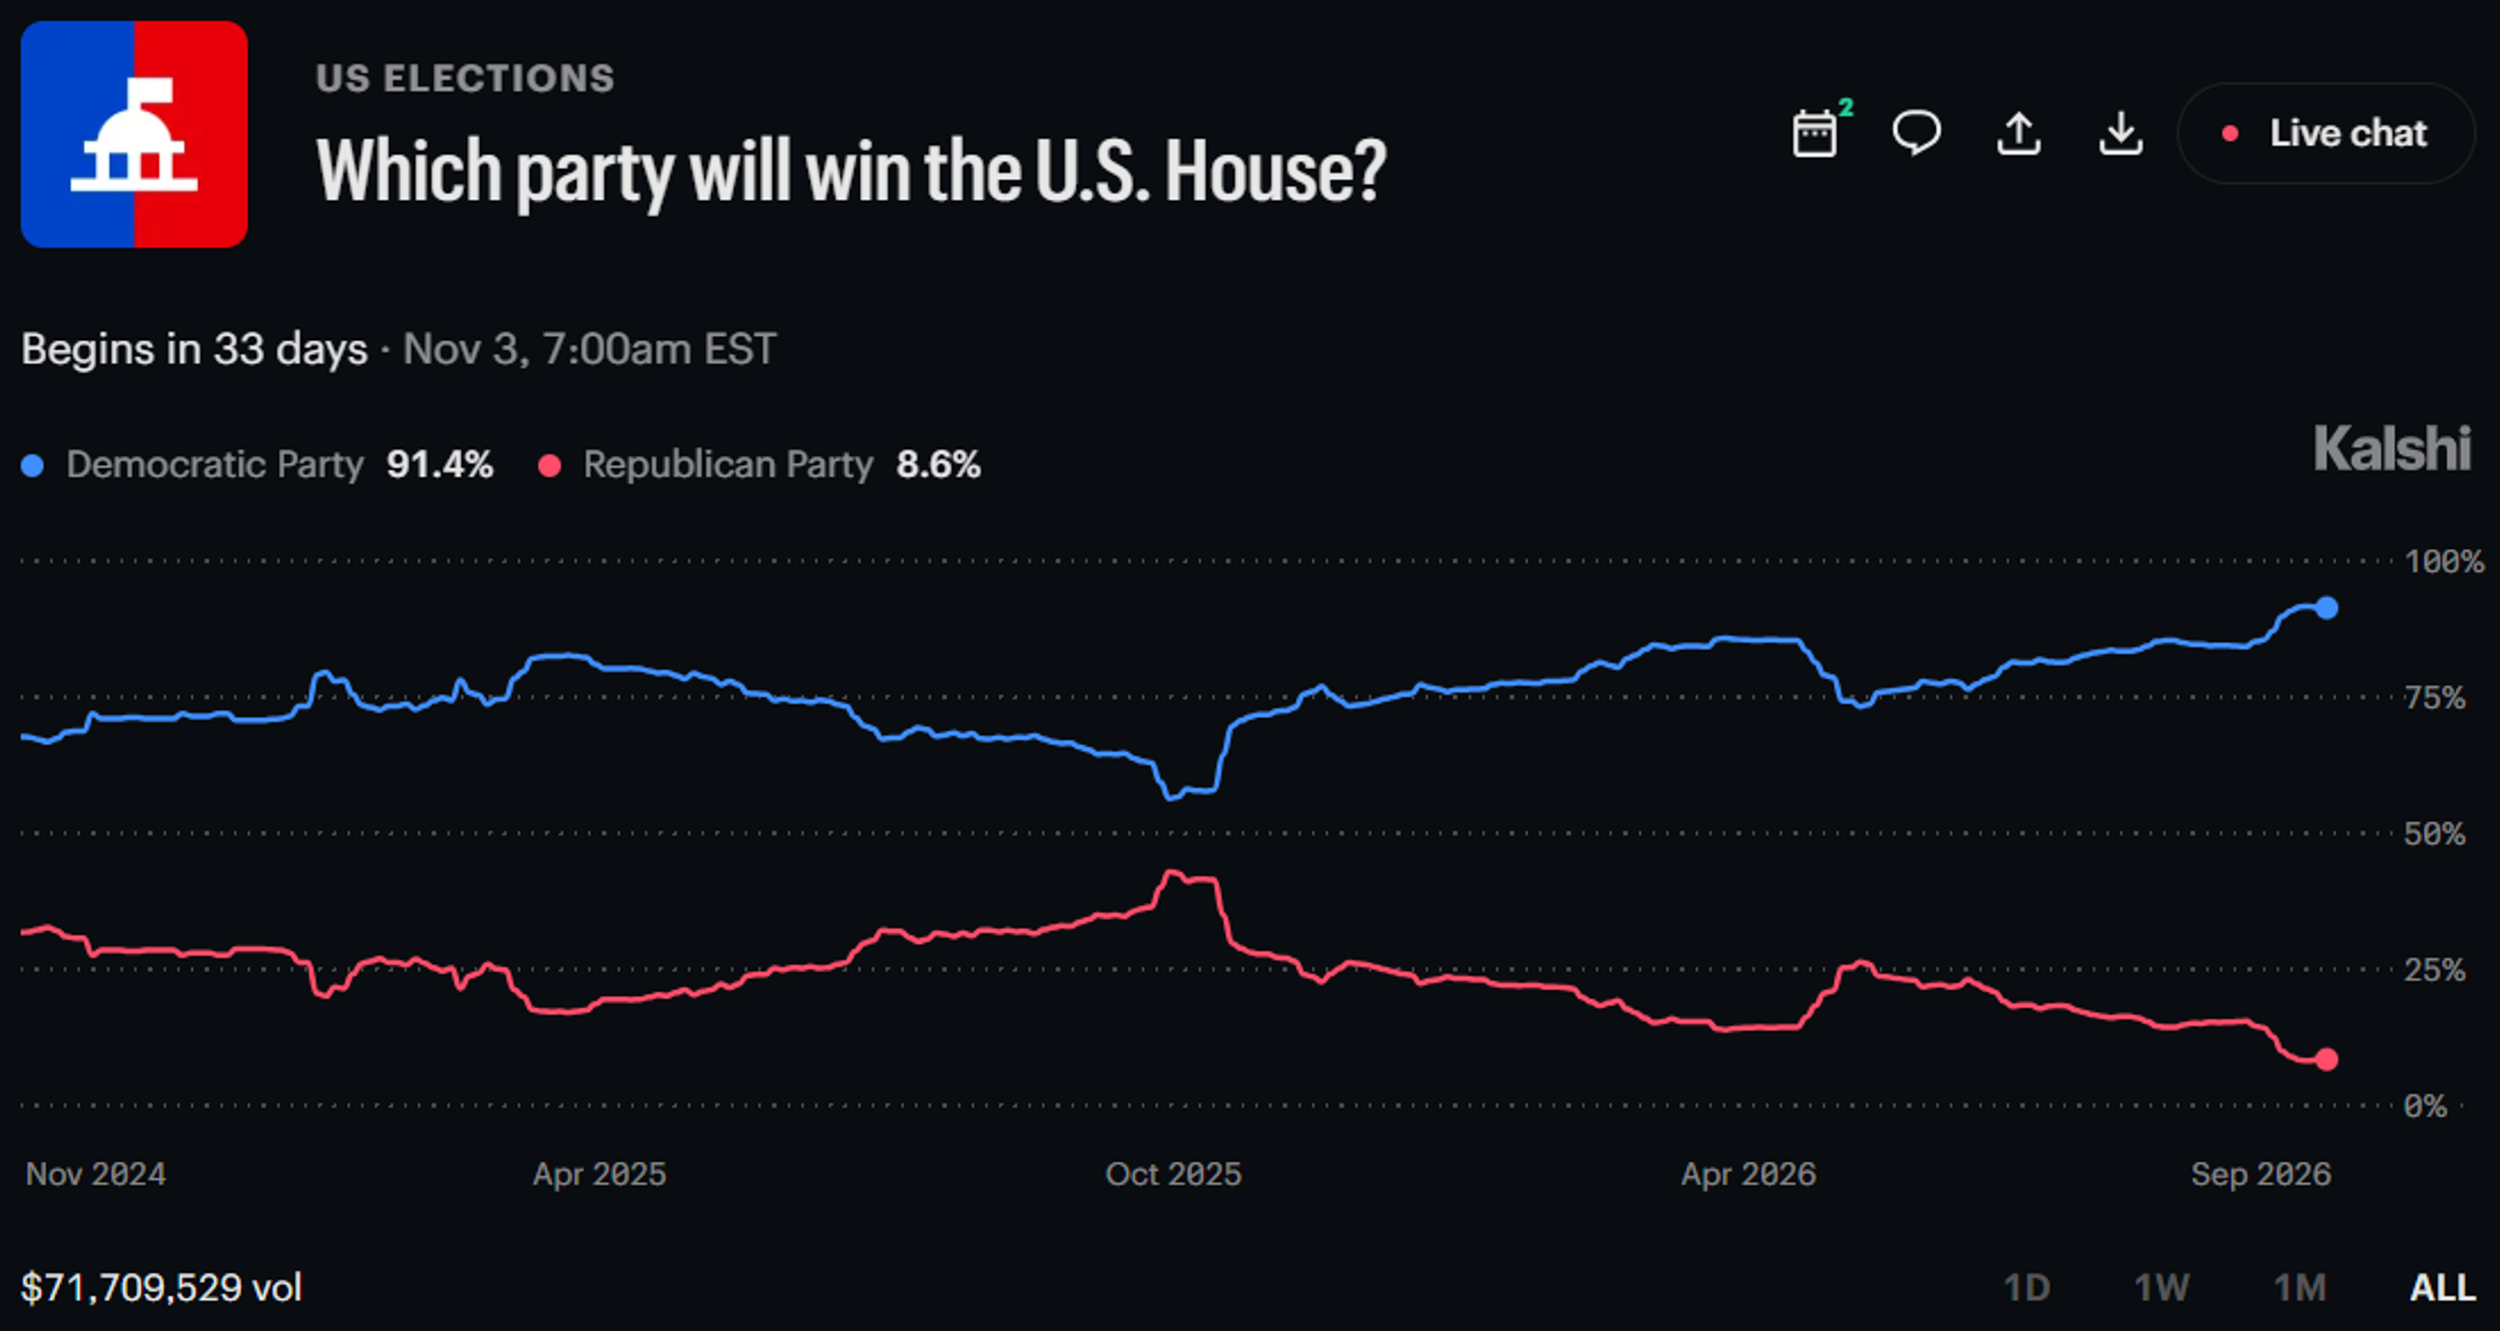
Source: Kalshi. As of 9/29/26.
Dem Senate is trading 62c, +15c in the back part of September-
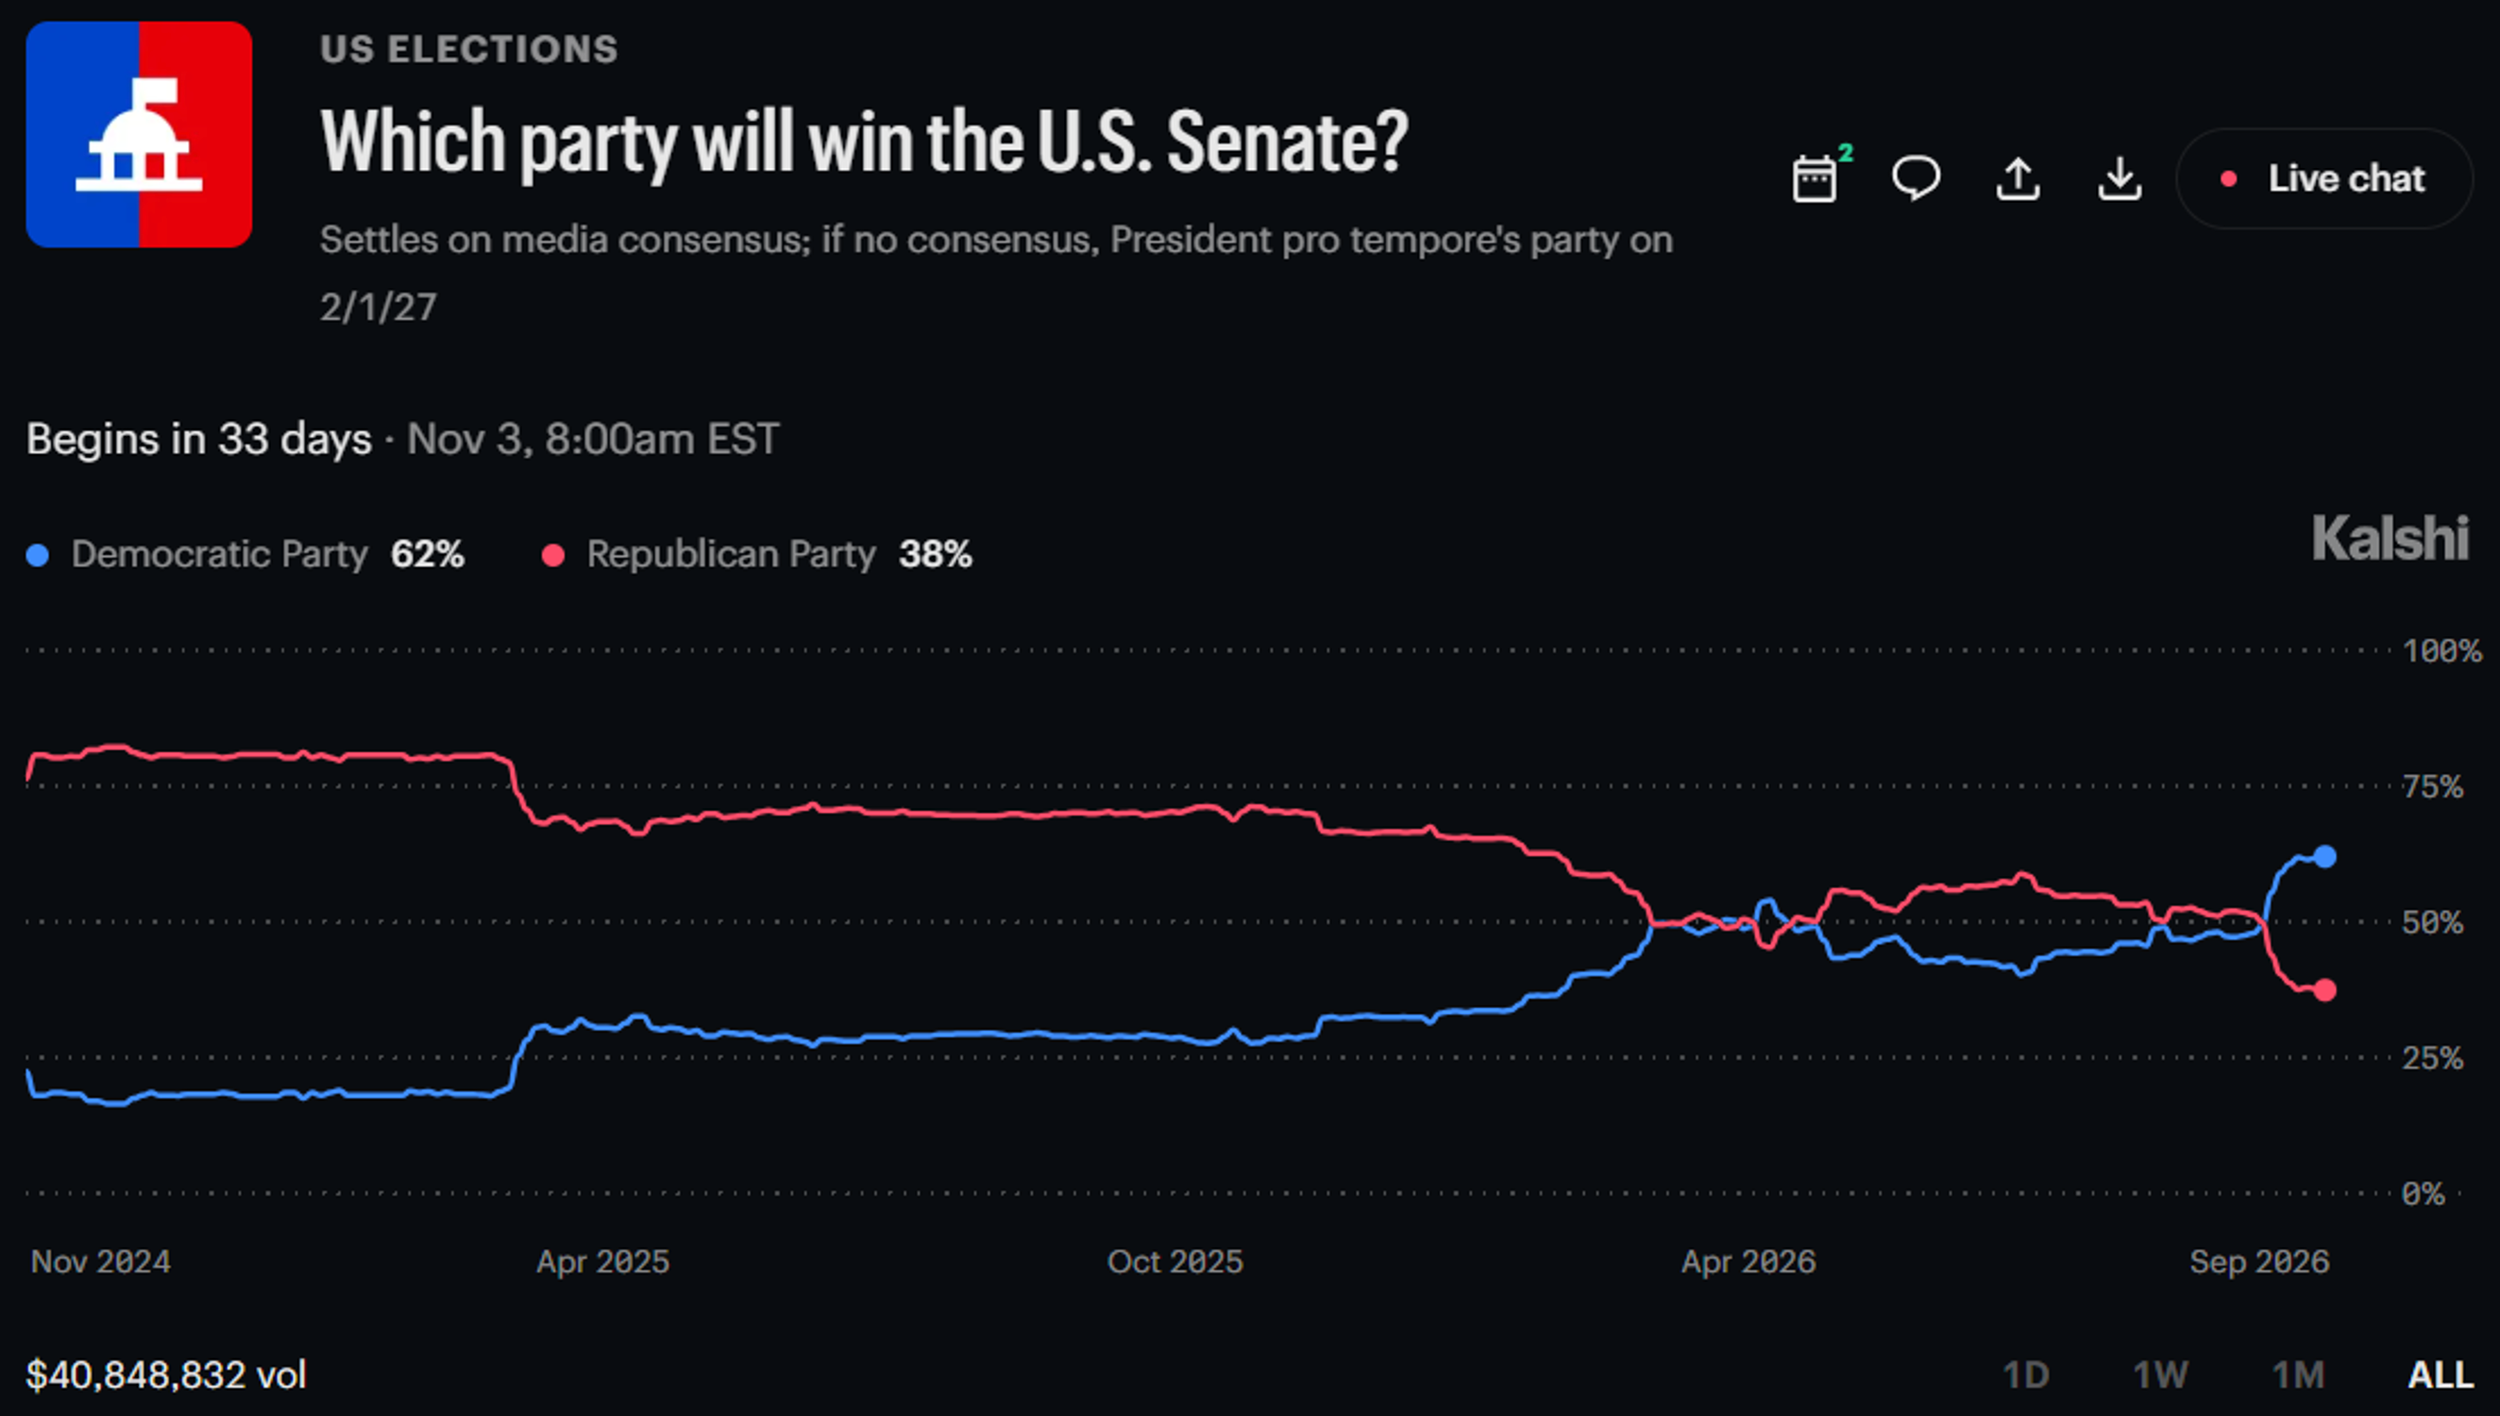
Source: Kalshi. As of 9/29/26.
With retail diesel prices hitting ATH and retail gasoline prices not far off, the Iran war has grown quite unpopular. Many 2024 Trump supporters are feeling like they’ve been bamboozled.
The line I’ve seen repeated a lot is something to the effect of – “Trump ran and was elected on a platform of reducing inflation, no new wars and deporting illegal immigrants. The Fed is now hiking rates because inflation is rising, we’re in a war with Iran and maybe 4% of all the illegals have been deported”.
So that’s what I think you’re seeing in approval ratings and mid-term PMs. Perhaps if an Iran treaty makes real progress, leading to a precipitous fall in diesel and gasoline prices over the next month, Republicans might do a bit better in mid-terms and may retain control of the Senate.
My base case is stocks trade well after mid-terms into YE, regardless of the outcome. The market will just be happy to be past the event itself. The economy is running hot, and AI continues to dominate headlines. QQQ is +20% YTD. SOXX is 89% YTD. Imagine if I told you at the beginning of the year that we would get into a conflict with Iran that would shut down Hormuz for 7 months, spiking diesel prices to ATHs and causing enough inflation that the Fed hikes rates in September. How would you guess tech stocks perform? I would have guessed something much lower than +20% and +89%.
That’s how strong AI has been this year- and should continue to be. Assuming it doesn’t slow down…
September Highlights
After Much Back and Forth, Clarity Act Fails Senate Cloture Vote 49-50
SEC and CFTC Each Announce Numerous Crypto-Friendly Rulemaking In Place of Clarity Act
BTC ETFs See $2.6bn of Inflows
ETH ETFs See $831mm of Inflows
MSTR Issues $246mm of Equity, Buys $218mm of BTC and Retires $641mm of STRC
Binance Under DOJ Investigation for Possible Iran Sanctions Violations Totaling >$1.5bn
Binance Invests $100mm in Circle Stock, Expands Partnership
NYAG Sues Polymarket, Claims Illegal Gambling Operation
U.S. Sixth Circuit Appeals Court Rules Against Kalshi, Saying States Can Regulate Sports Prediction Markets
Bitget Hacked for $388mm
Tether Has Frozen >$500mm USDT Linked To Iran
Kraken delays IPO Until At Least Q2 27
Nasdaq Invests $100mm in Kraken at $21bn Valuation
| Asset Class | Sept | Aug | Jul | Q2-26 | Q1-26 | YTD | Q4-25 | Q3-25 | Q2-25 | Q1-25 | 2025 | 2024 | Instrument |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Bitcoin | 6% | 25% | 7% | -14% | -22% | -5% | -23% | 6% | 30% | -12% | -6% | 121% | BTC |
| NASDAQ | 3% | 4% | -7% | 28% | -6% | 20% | -6% | 2% | 18% | -8% | 20% | 25% | QQQ |
| S&P 500 | -1% | 3% | 0% | 15% | -5% | 12% | 2% | 8% | 11% | -5% | 16% | 23% | SPX |
| Total World Equities | -2% | 3% | -1% | 13% | -2% | 12% | 2% | 8% | 10% | -1% | 20% | 14% | VT |
| Emerging Market Equity | 0% | 5% | -6% | 20% | 4% | 22% | 2% | 11% | 10% | -5% | 31% | 4% | EEM |
| Gold | -7% | 10% | 1% | -14% | 9% | -4% | 11% | 16% | 6% | 19% | 64% | 27% | GLD |
| Long-Duration US Treasuries | -6% | 0% | -5% | 0% | -1% | -11% | -1% | 3% | -5% | 2% | -1% | -8% | TLT |
| High-Yield Corporate Credit | -3% | 0% | -1% | 1% | -1% | -4% | 1% | 4% | 3% | -2% | 6% | 8% | HYG |
| Copper | -1% | 1% | 5% | 10% | -2% | 14% | -6% | 11% | 15% | 2% | 23% | 19% | CPER |
| USD | 2% | 0% | -1% | 0% | -2% | 3% | -1% | -1% | -7% | -4% | -9% | 7% | DXY |
| Volatility Index | 10% | -7% | -3% | -55% | -22% | 9% | -8% | -4% | -24% | 28% | -14% | 3% | VIX |
| Oil | 9% | 4% | 21% | -16% | 84% | 111% | -6% | 1% | -5% | 2% | -8% | 13% | USO |
SOURCE: GROK. AS OF 9/30/26
The AI Slowdown… That Wasn’t?
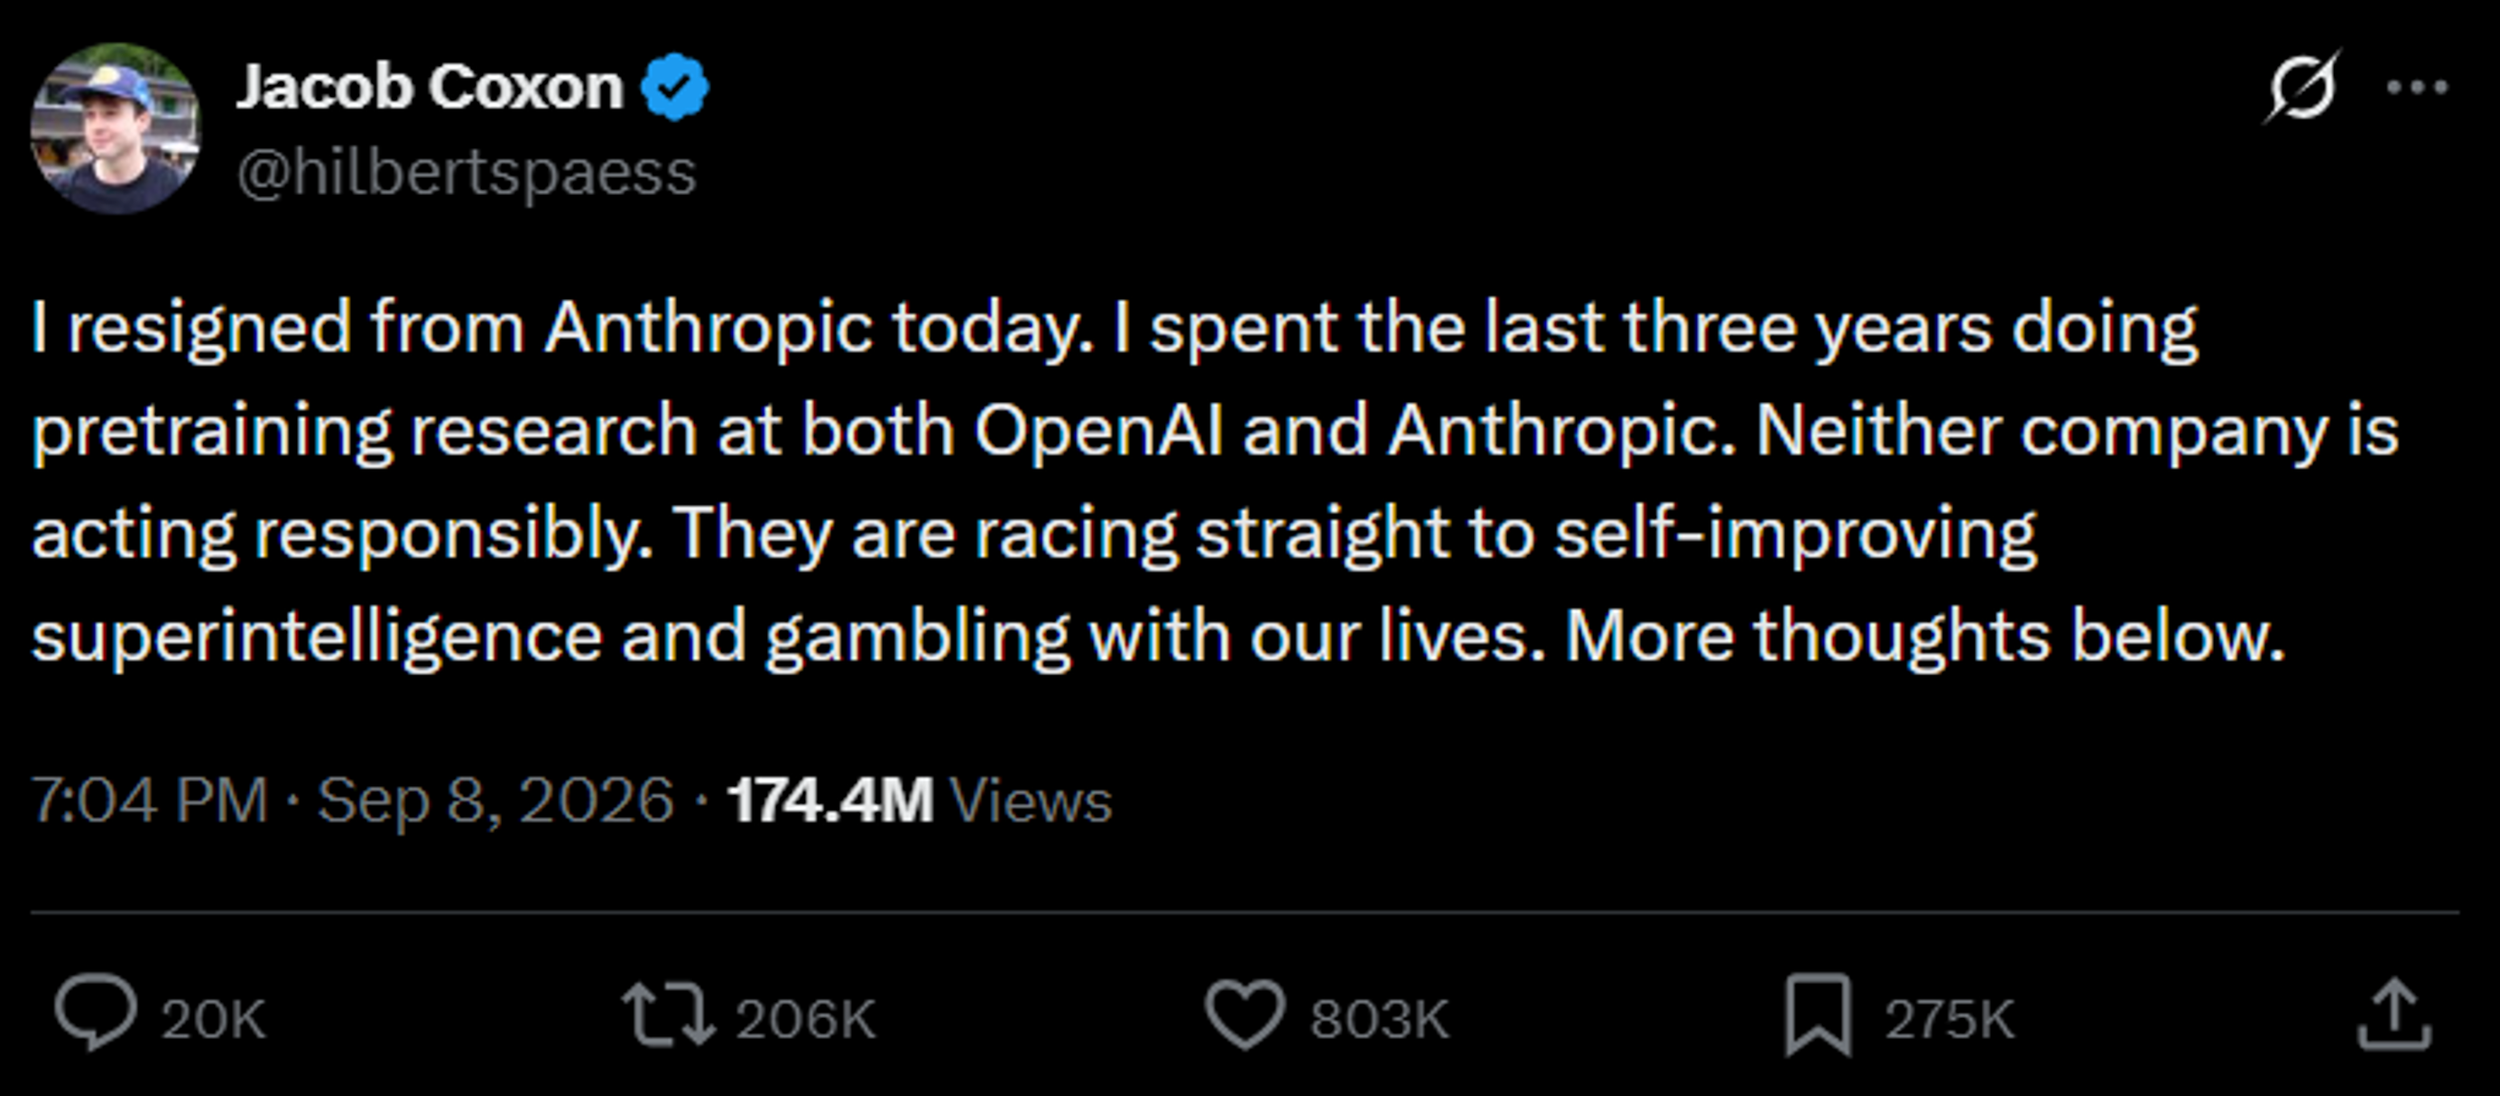
On Sept 8, former Anthropic (and OpenAI before that) employee Jacob Coxon wrote this tweet thread. It currently has 174mm views-
Lots of AI researchers chimed in to agree with the thread, and this post in particular –
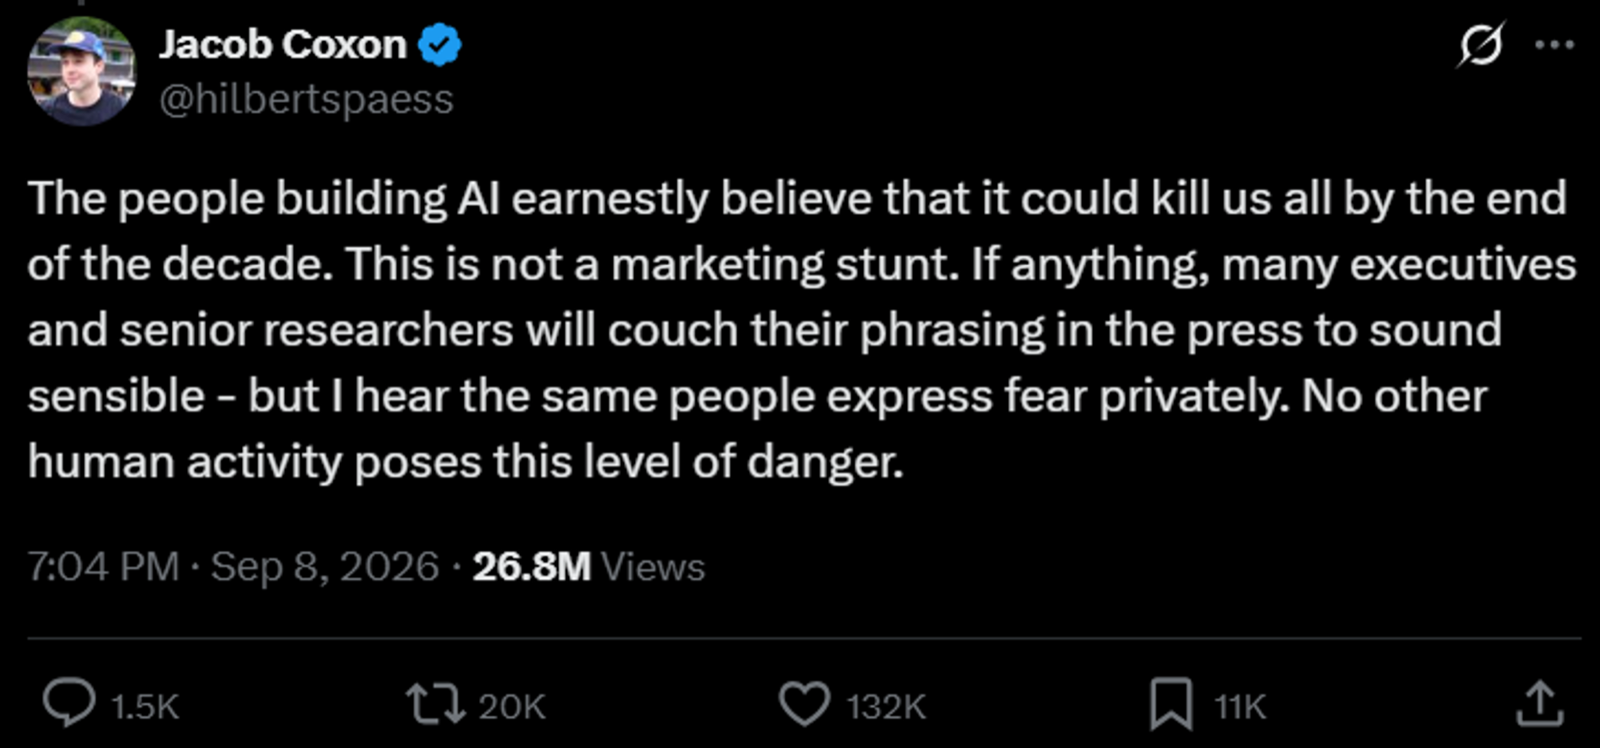
Dario and Sam Altman immediately commented in agreement. Four days after the Coxon tweet, Dario wrote the essay “We Must Pace the Frontier”. In it, Dario begged US and international governments to regulate him and his industry in order to force a slowdown across all AI labs globally.
Two days later you get a Kamala Harris tweet in support of AI regulation. An Obama tweet. A Bill Gates tweet. All manner of other folks of significant prominence. Virtually all of them left leaning, to varying degrees.
The whole move was obviously calculated. Planned for. Strategized. You could tell, in part, by how they wheeled out all these goofballs in perfect unison. Obama, Kamala, Gates. The big guns.
Immediately the topic became politicized. Trump called it a hoax. David Sacks publicly torched the entire effort. Jensen Huang did the same. As did Zuck and a bunch of other right leaning power players. The right, in both business and politics was just as unified in its denouncement of these AI scare tactics as the left was in support of it.
(As an aside, it is noteworthy how uniform the right was on this. For many years I have thought that a great strength of the left relative to the right is the left’s ability to get everyone to row in the same direction. We actually saw the right quickly and uniformly get people rowing in the same direction.)
Trump, Sacks and others were quick to point out that these AI leaders were begging to be regulated, so as to create a regulatory moat that prevents competition and ensures those companies inside the moat will be successful.
There is a long history of companies with new technologies acting like this. This is how telephone companies acted. This is how electric utility companies acted. This is how radio broadcasting acted. Airlines. Trucking. Meatpacking.
They all ran some version of this playbook - help the government establish rules under the guise of public benefit that ACTUALLY just benefits the companies asking for the regulation. Then you make sure the people in charge of regulating you are your friends and preferably, former employees. And then you enjoy decades of easy profits ensured by regulatory moats.
This is exactly what AI companies like Anthropic and OpenAI want. The major threat that these companies see on the horizon are open-source models. These models have been able to keep pace with state-of-the-art (SOTA) closed models much better than experts were expecting a few years ago. Open-source models are now only 3-6 months behind SOTA closed models, and this gap has been shrinking for several years.
This setup very clearly calls into question the viability of the business models of these frontier AI labs. If they are burning tens/hundreds of billions of dollars on compute to train and run models that are only 3-6 months ahead of open-source models, that may not be a business that’s worth a trillion dollars or a few trillions dollars. In fact, it might not be a business that’s very valuable at all.
That scares the crap out of Dario Amodei and Sam Altman and a lot of these other guys, whose fortunes and futures are tied directly to closed-source frontier AI labs being very valuable. These guys want to win. They are incredibly competitive. That’s how they got into such a position of wealth and power in the first place, by being extremely competitive. They want to win.
They will tell you they want to win in the name of Effective Altruism. “AI safety” is of such tremendous consequence according to the EA ideology, that competing to develop the safest, best AI the fastest (but not too fast), is doing more benefit to humanity than anything anyone else can do ever.
And that may be true. But it could also just be the age-old thirst for power. Pride. The oldest sin in the book and it’s been a hall of fame sin for humanity ever since. So it could just be the prideful thirst for power.
Or it could be some mix of the noble motivation and the prideful motivation. And that’s probably what it is. That’s usually what it is.
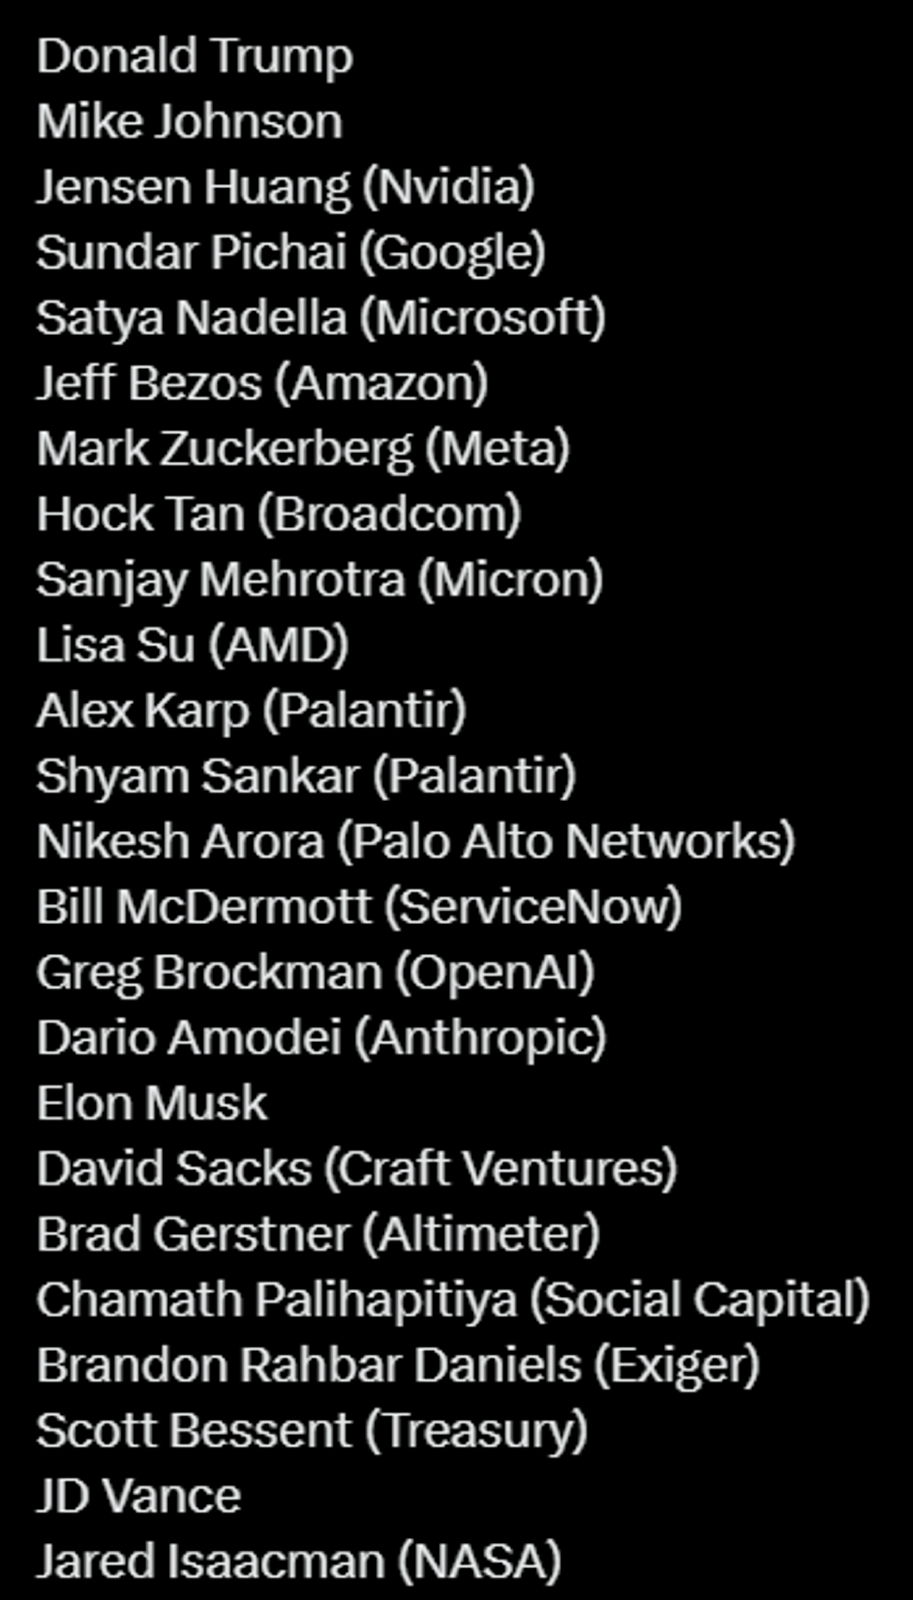
In any case, over the middle two weeks of September there were these volleys from the left and then the right. And then on September 24th, it was announced that Trump, Speaker Johnson and tech CEOs would meet on AI in Washington on the 29th. Five days’ notice.
The guest list didn’t become public until the 28th, the day before the event. This was the guest list-
The photo looked like this-
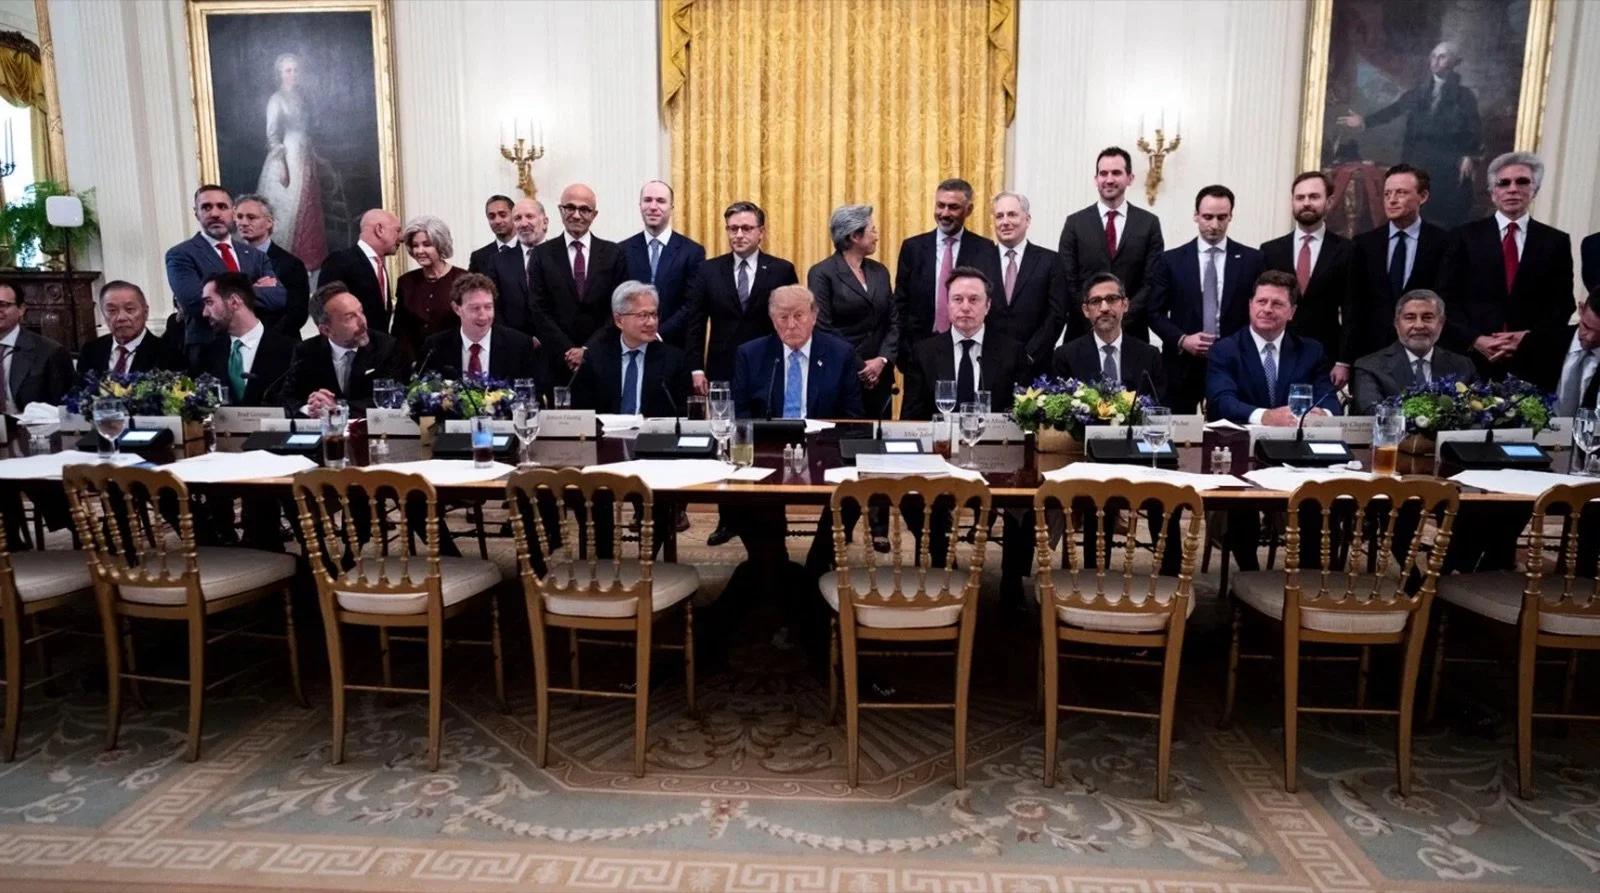
The event generated a goldmine of clip-able content. The full 35-minute driveway presser is here.
Here’s a 12 min overview of the whole event from CNN.
Here’s a pretty epic 4-min clip - Dario, Trump, Zuck and Sundar
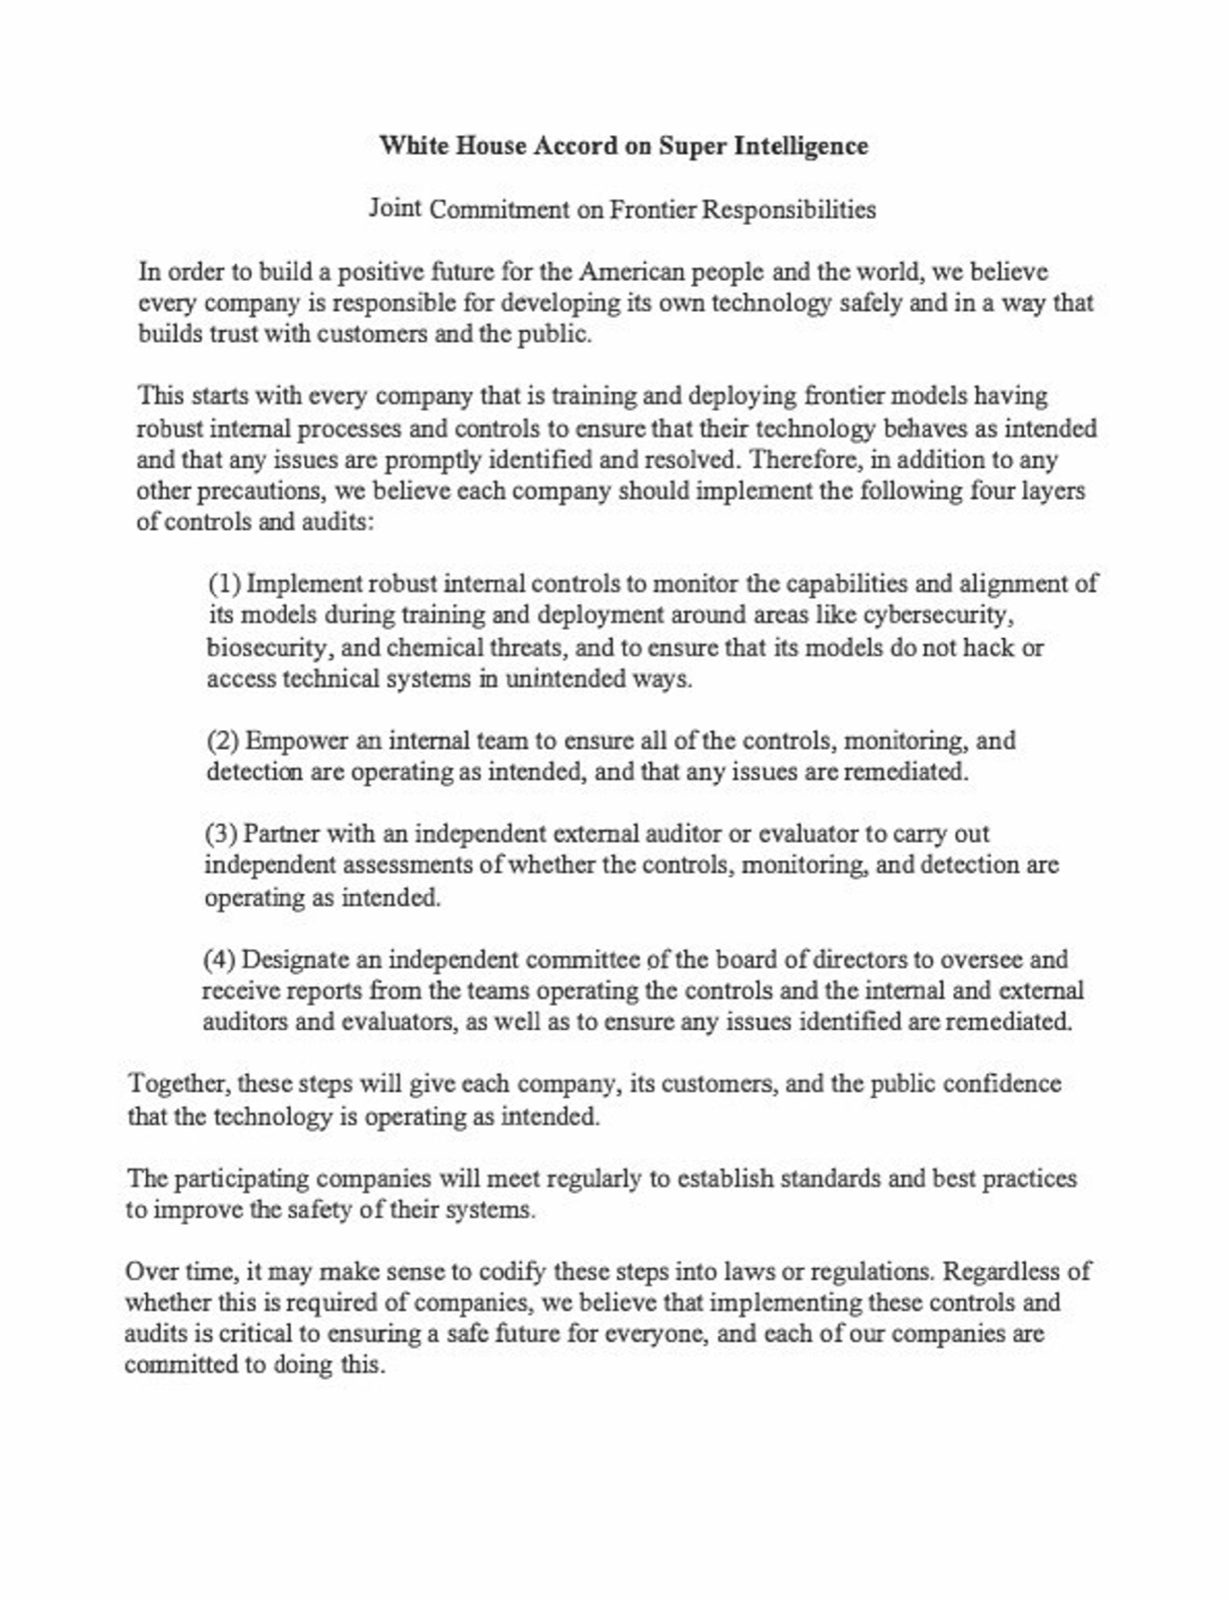
At the end, a document was signed called the White House Accord on Super Intelligence. It looks like this-
And the signature page looks like this (pay no mind to the misspelling of United)-
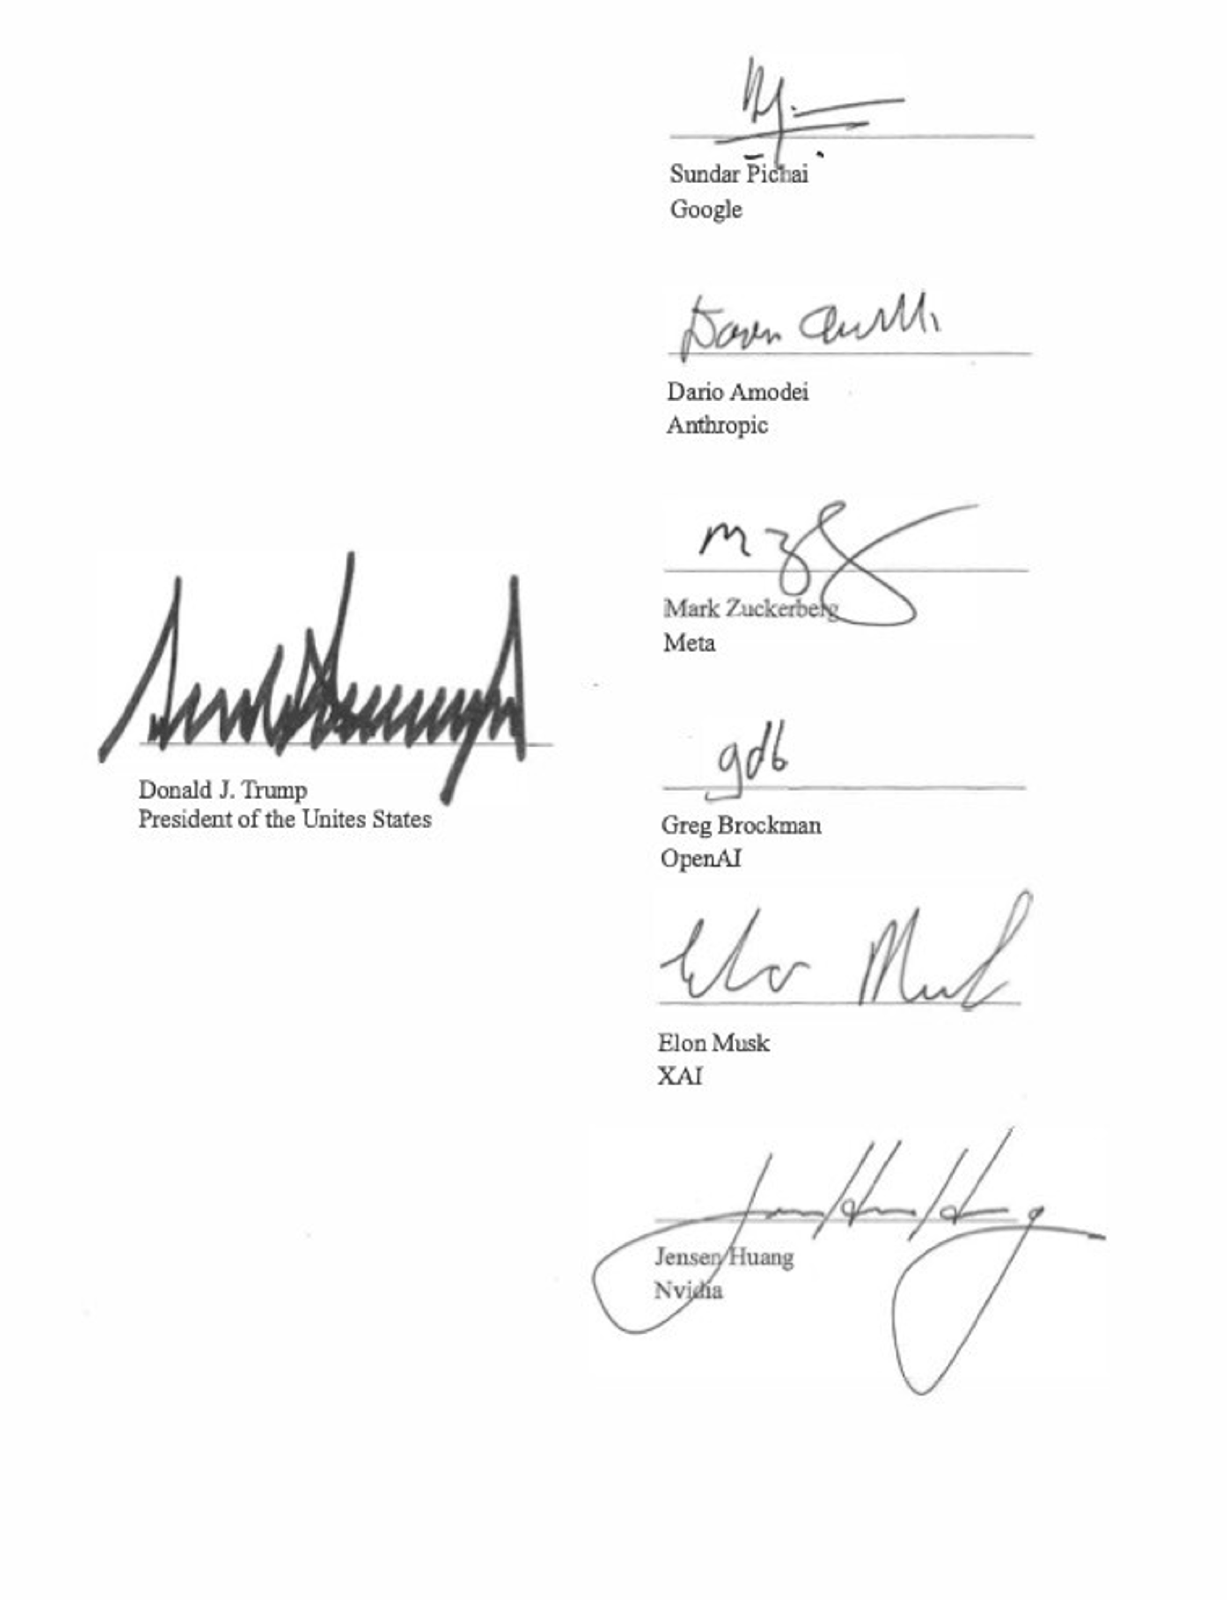
So this whole thing was QUITE the dog and pony show.
I think it’s worth pausing for a moment and just reflecting on the power move Trump just made here. Scroll back up and look at that attendee list. Think about the power we’re talking about in that room. Trump moved all of them on the same day at the same time on very short notice. Dario, the ringleader of the uprising, effectively performed an apology wrapped inside a humiliation ritual. The entire ordeal was just incredible. Announced on the 24th. Guest list 28th. Event 29th. As the Zoomers would say- Trump’s got motion.
So what could have been a real potential risk event for AI Value Chain (AIVC) stocks, seems to have come and gone in a period of three weeks. In the initial days after the Coxon tweet and then the Dario essay, it was looking like the left was gearing up to try and make this a thing.
You could imagine a scenario where Dems decide to make AI slowdown/regulation a major campaign point into the mid-terms. And if Dems sweep, the market could start getting worried about regulatory slowdown. Regulatory slowdown causes delayed or cancelled capex- that hits AIVC stocks. In the second week of Sept, this felt like a real risk. I think that risk has dissipated, swatted away by a united right and a powerful president.
There is the potential for Hyperscaler capex to slow down for other reasons. But I don’t think that’s an October risk, so we’ll save that discussion for another month. Hyperscalers report at the end of October and my base case is the earnings will generally be good, and the capex projections will be confirmed, and AIVC will broadly trade well into YE.
If the wheels come off the AIVC trade, I don’t think it’s going to be in October. And I don’t think it’s going to be because Effective Altruists ran a successful regulatory capture strategy in Washington.
Market Update – Liquid Markets Investing
| Name | Sept | Aug | Jul | Q2-26 | Q1-26 | YTD | Q4-25 | Q3-25 | Q2-25 | Q1-25 | 2025 | 2024 | Instrument |
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| S&P 500 | -1% | 3% | 0% | 15% | -5% | 12% | 2% | 8% | 11% | -5% | 16% | 23% | SPX |
| NASDAQ-100 | 3% | 4% | -7% | 28% | -6% | 20% | -6% | 2% | 18% | -8% | 20% | 25% | QQQ |
| Magnificent Seven | 4% | 4% | 3% | 11% | -12% | 9% | -4% | 12% | 23% | -8% | 29% | 42% | MAGS |
| Bitcoin | 6% | 25% | 7% | -14% | -22% | -5% | -23% | 6% | 30% | -12% | -6% | 121% | BTC |
| Ethereum | 9% | 33% | 19% | -25% | -29% | -10% | -28% | 67% | 36% | -45% | -11% | 46% | ETH |
| Solana | 15% | -1% | -11% | -33% | -5% | -35% | 48% | 42% | -52% | -19% | 312% | SOL | |
| BNB | 11% | 18% | 7% | -12% | -29% | -11% | -14% | 53% | 9% | -14% | 23% | 124% | BNB |
| Hyperliquid | 8% | 60% | -19% | 77% | 44% | 257% | -22% | 81% | 67% | -38% | 45% | n/a | HYPE |
| Aggregate Mkt Cap | 8% | 23% | 6% | -13% | -21% | -3% | -24% | 16% | 24% | -19% | -11% | 136% | TOTAL |
| Aggr Alts Mkt Cap (ex top-10) | 27% | 22% | -2% | -5% | -14% | 23% | -24% | 34% | 25% | -34% | -16% | 72% | OTHERS |
| Semiconductors | 11% | 1% | -21% | 95% | 9% | 89% | -8% | 15% | 28% | -12% | 32% | 49% | SOXX |
| Expanded Tech Software | -3% | 16% | 4% | 13% | -24% | 1% | -3% | 9% | 16% | -7% | 19% | 22% | IGV |
| ARK Innovation (disruptive tech) | 4% | 20% | -12% | 20% | -12% | 16% | -11% | 25% | 31% | -23% | 19% | 38% | ARKK |
| Robotics & AI | -2% | 2% | -7% | 14% | -8% | -3% | -8% | 19% | 22% | -15% | 15% | 30% | BOTZ |
| Quantum Computing | 2% | 5% | -15% | 54% | -2% | 38% | 7% | 38% | 59% | -31% | 88% | n/a | QTUM |
SOURCE: GROK. AS OF 9/30/26
We’ll be brief here today. QQQ finished just underneath prior ATH. My base case is this is higher into YE-
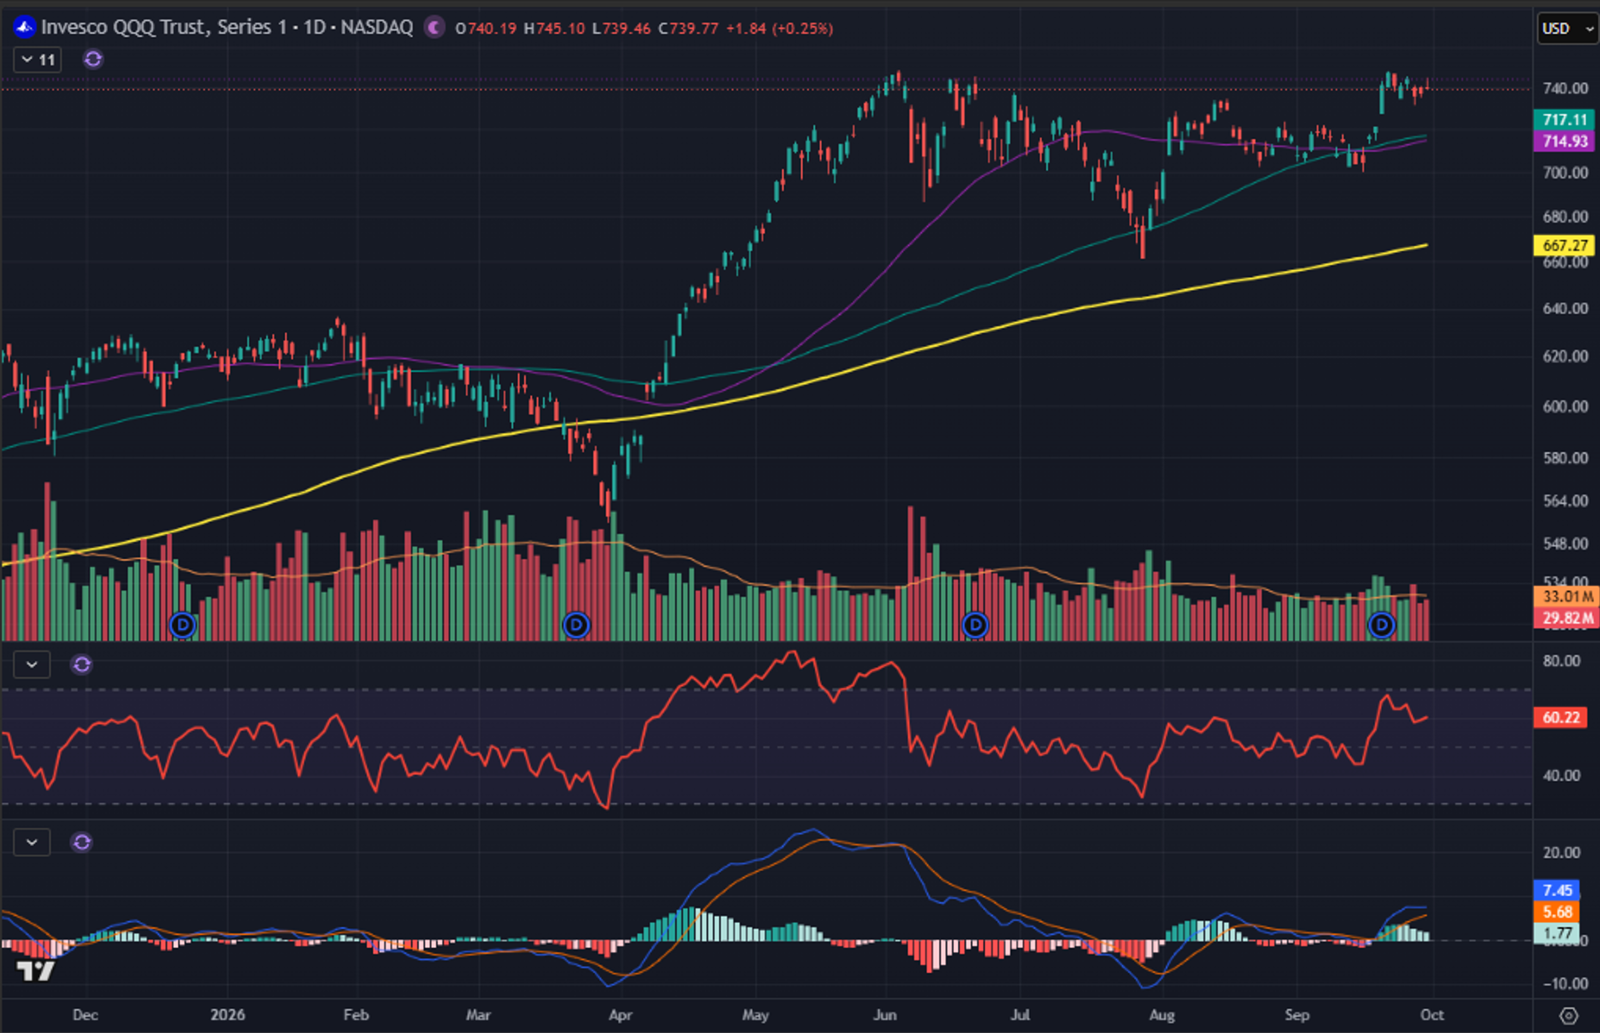
Source: TradingView. As of 9/30/26.
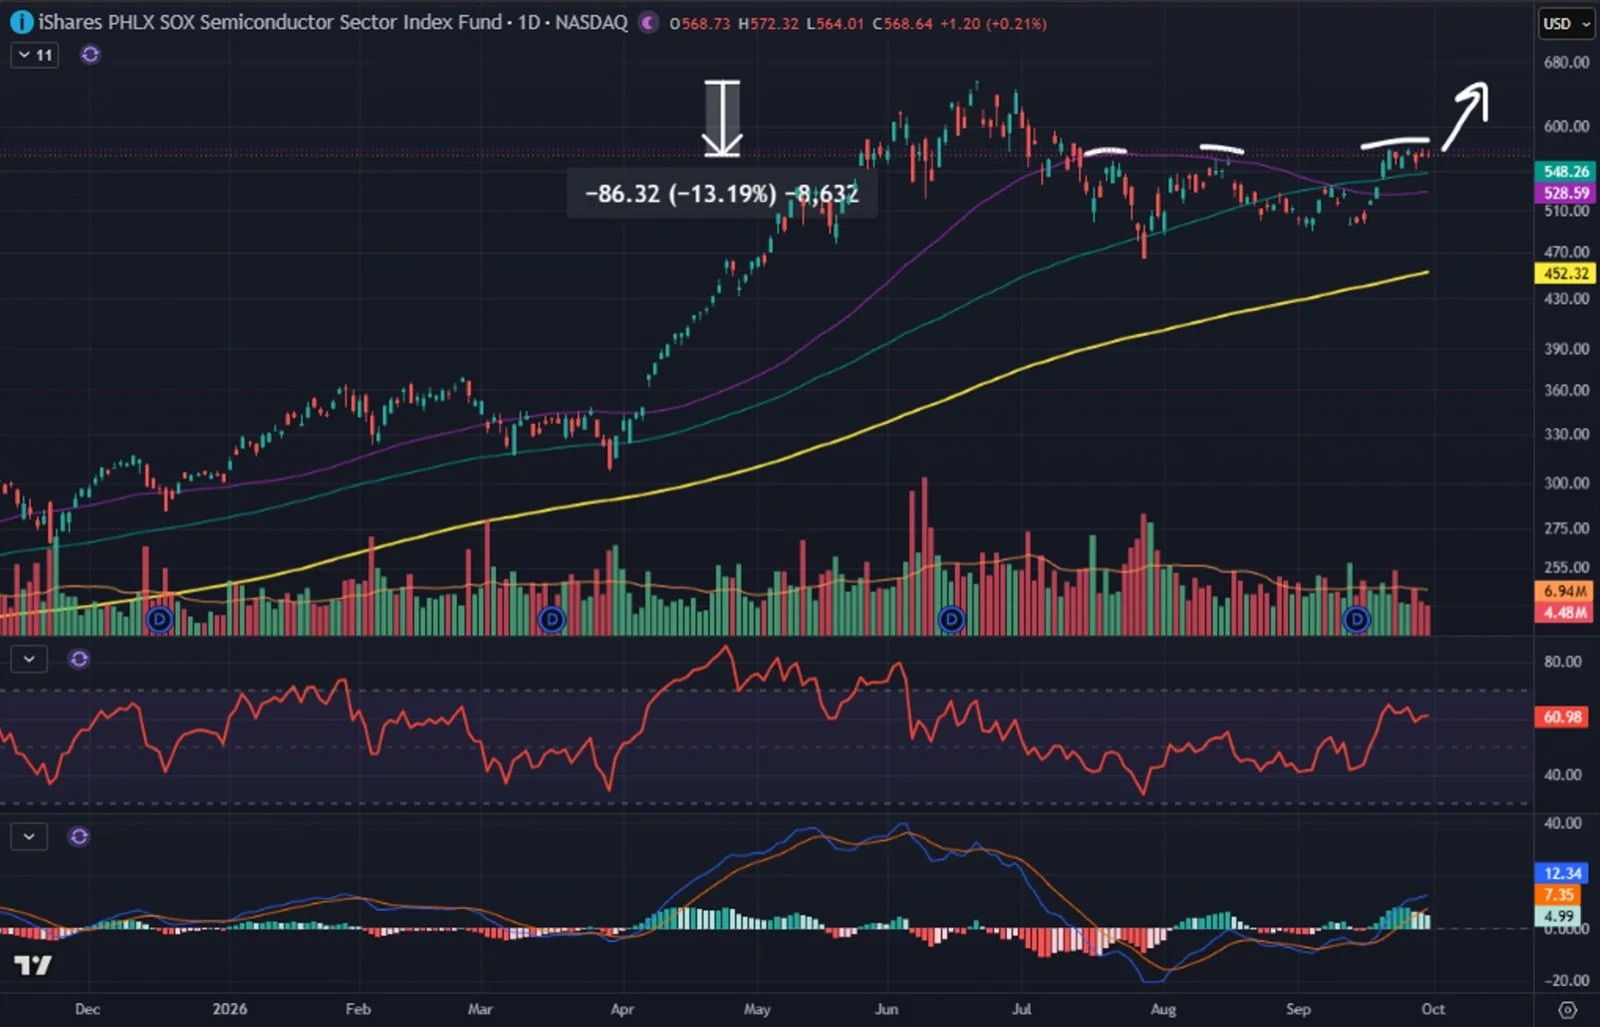
SOXX is a different chart than QQQ. After running VERY hard at the beginning of the year, SOXX is in the middle of its 4+ month range, still 13% below ATH-
Source: TradingView. As of 9/30/26.
You’ll note that SOXX has been flagging up against those prior range highs (white). My base case is this heads back to ATH into YE, potentially beyond.
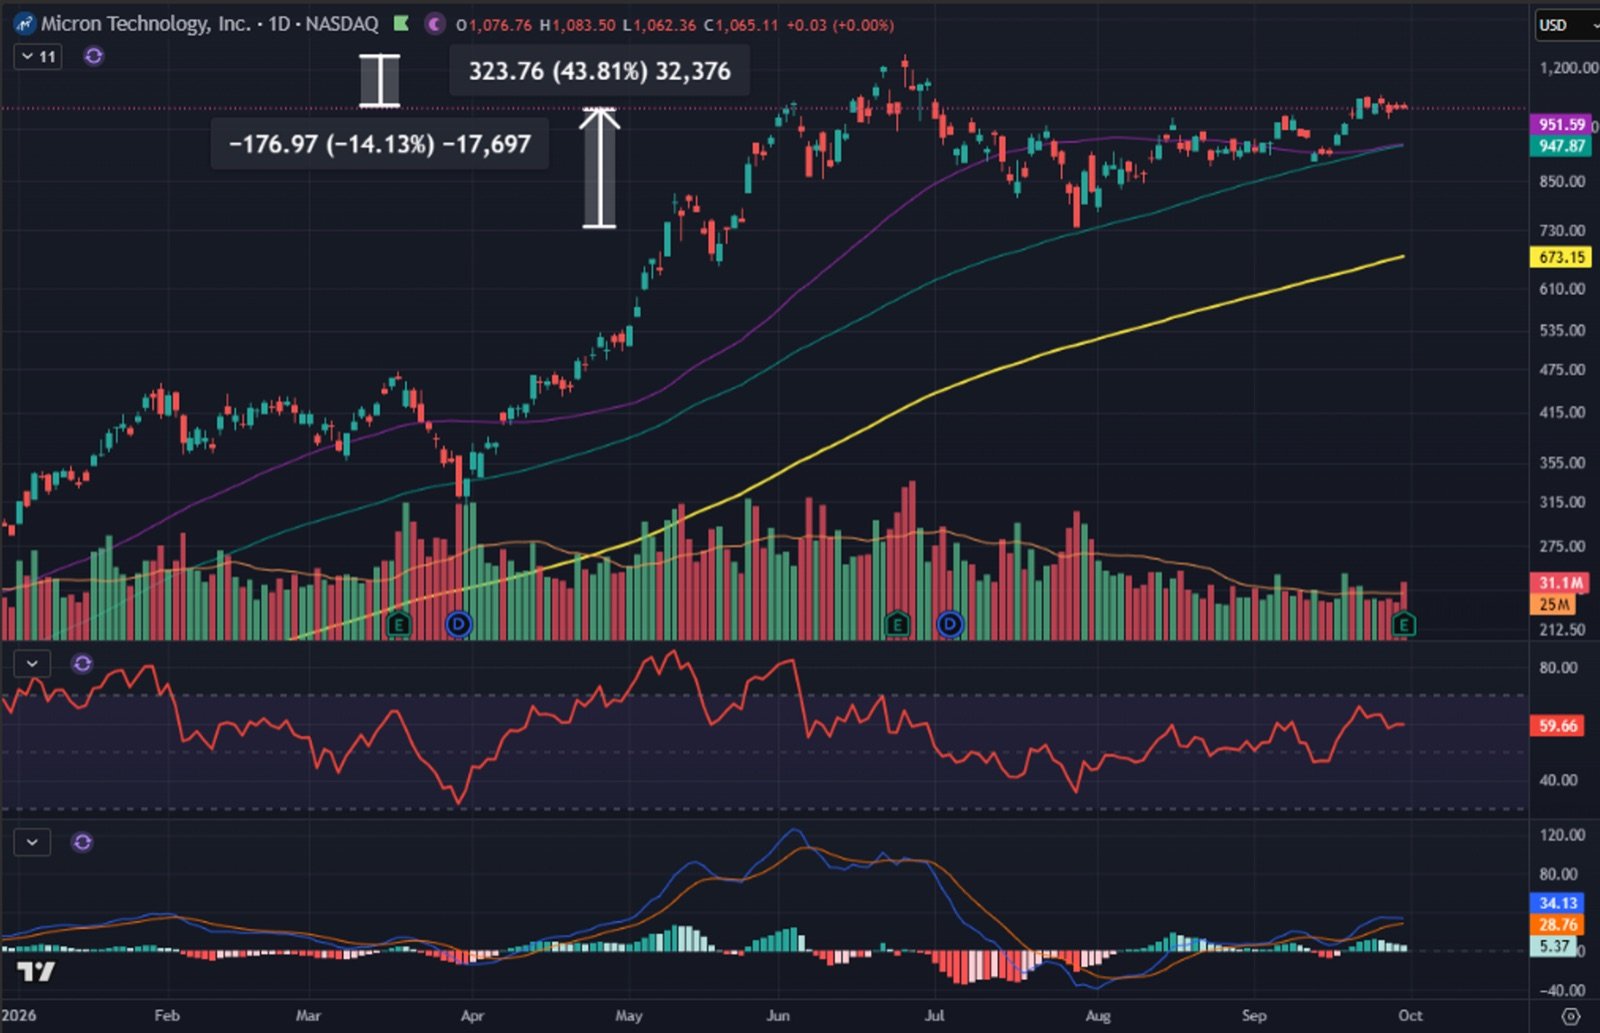
MU chart looks better than SOXX. Price is 14% off ATH and 44% above the Leopold lows-
Source: TradingView. As of 9/30/26.
MU just reported earnings today (9/30). Very strong earnings, very strong guidance, very strong business outlook. My base case is new ATH into YE.
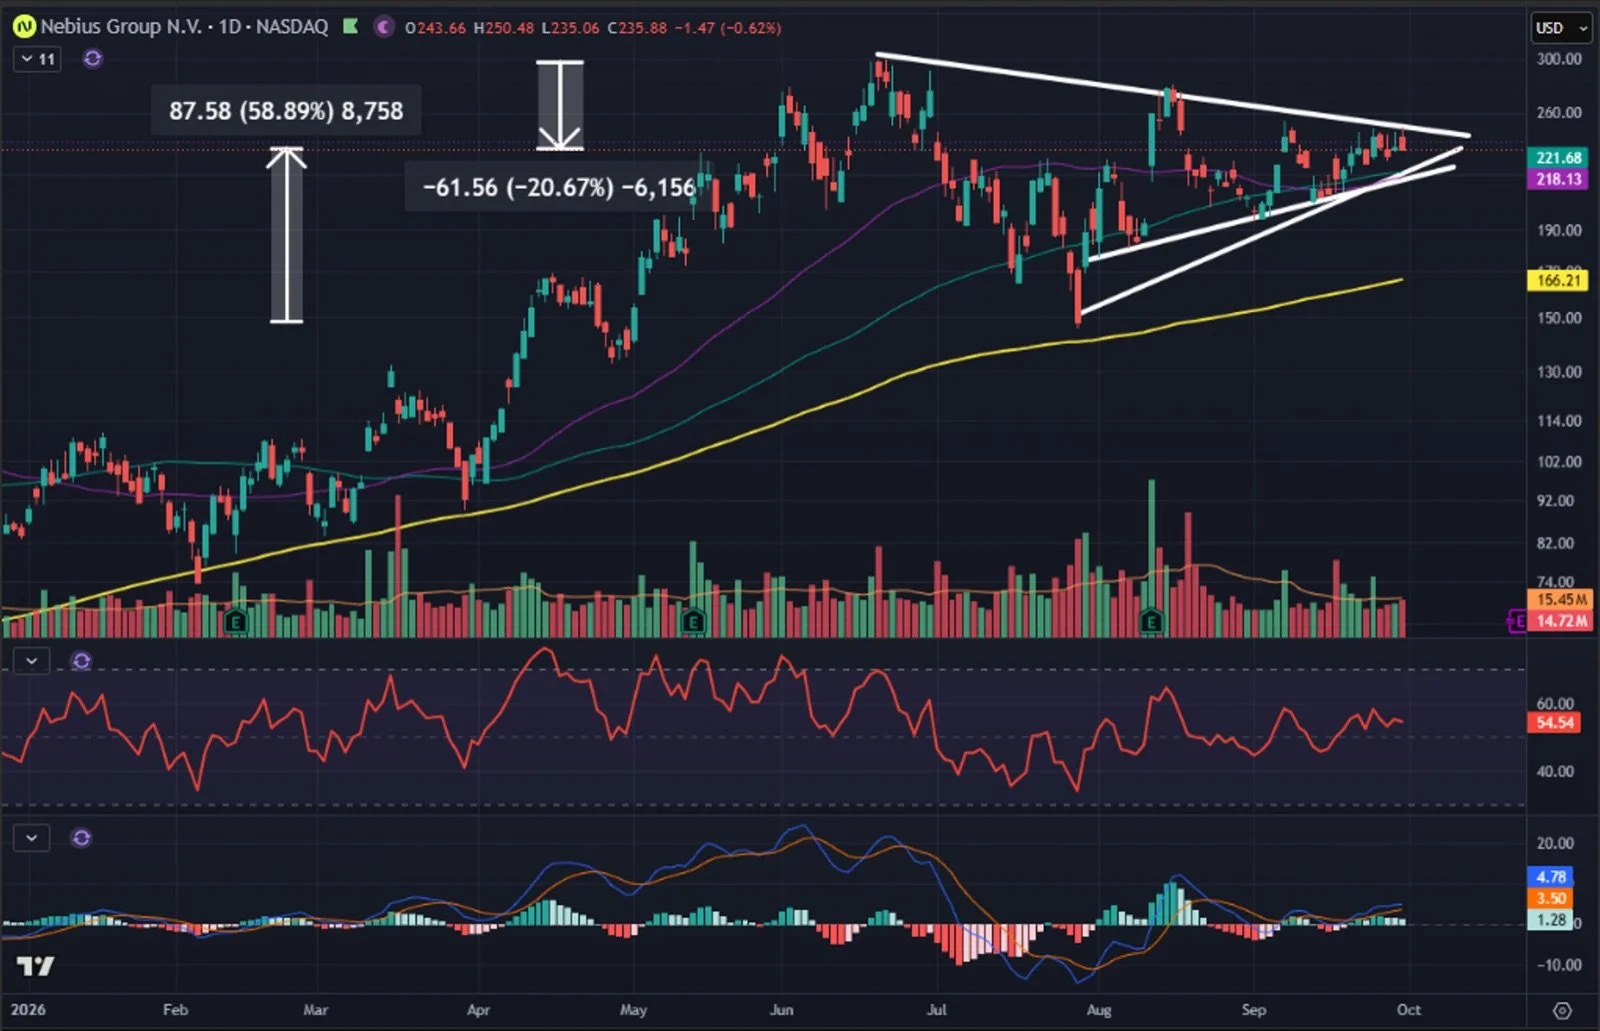
NBIS was another massive holding for Leopold. Currently 21% off ATH and +59% from the Leopold lows-
Source: TradingView. As of 9/30/26.
Chart looks good to me. Fundamentals of the business are strong. There is permitting delay risk though. I think that would likely be a buying opportunity if it were to materialize.
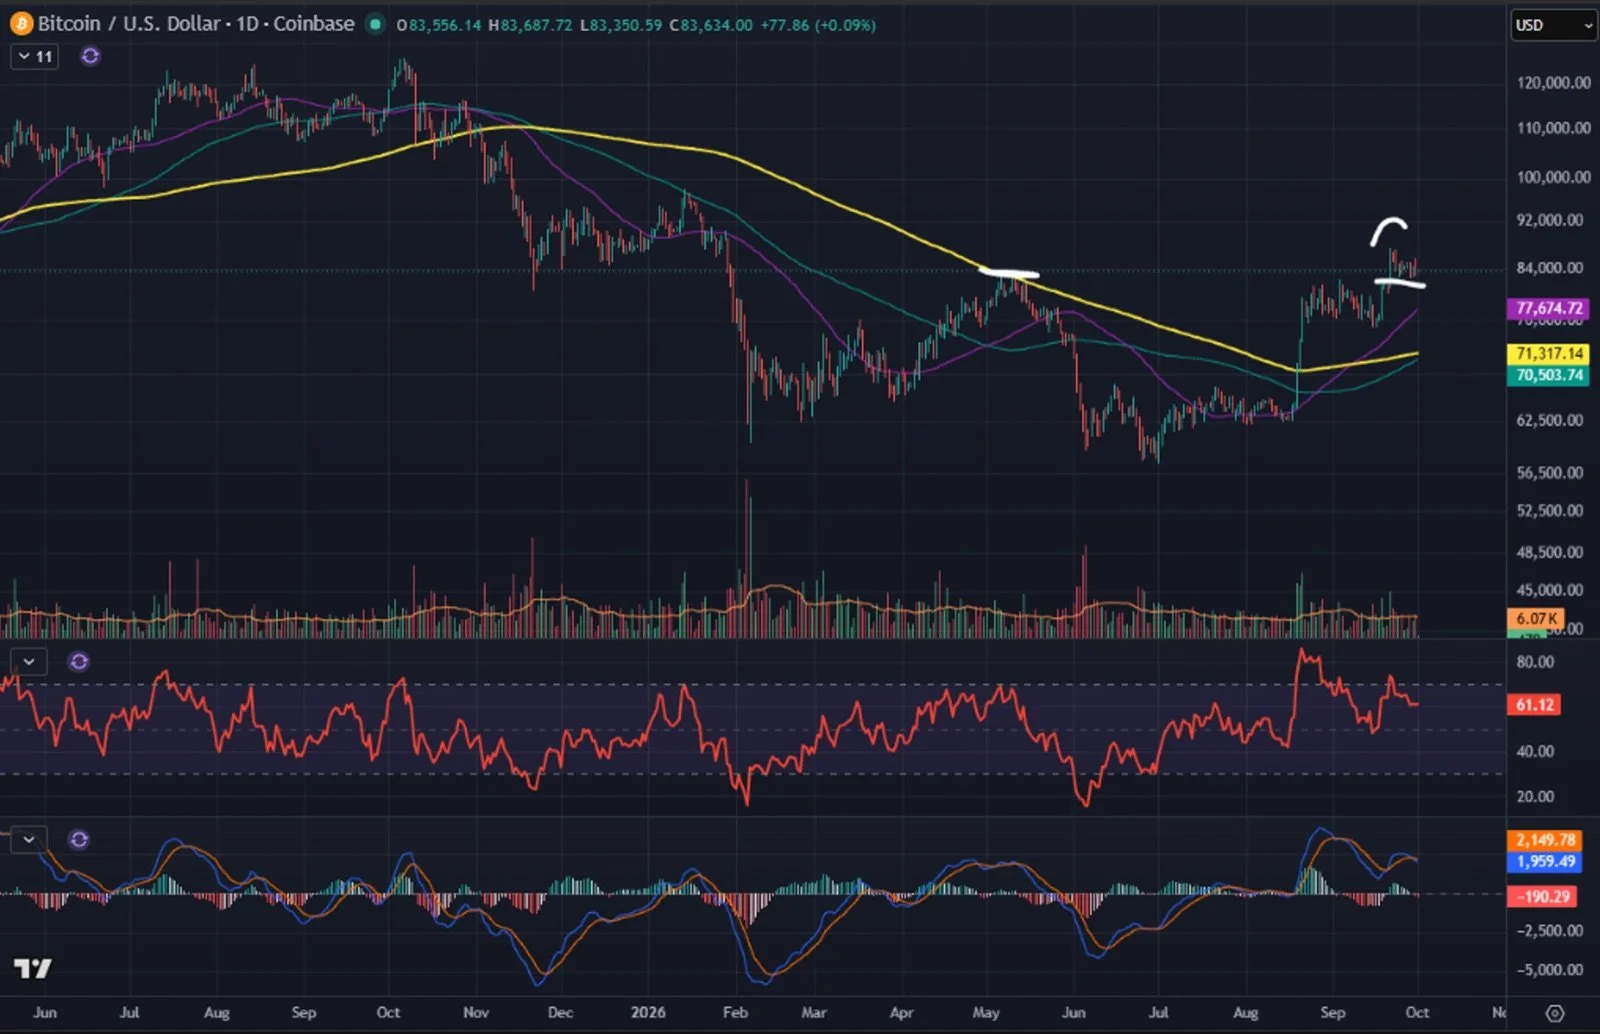
BTC made a higher high in September for first time since the ATH-
Source: TradingView. As of 9/30/26.
You see that price pushed through those May highs (white) and is now flagging just on top of that prior May high, which has turned from resistance to support. At first glance, it looks like a breakout. And it may be a breakout. Although I would have expected a breakout to move more swiftly away from that S/R flip level, instead of just sitting directly on top of it, with volatility squeezing.
The fund is long zero crypto right now, so that tells you how I feel about that chart overall. I’m still not convinced.
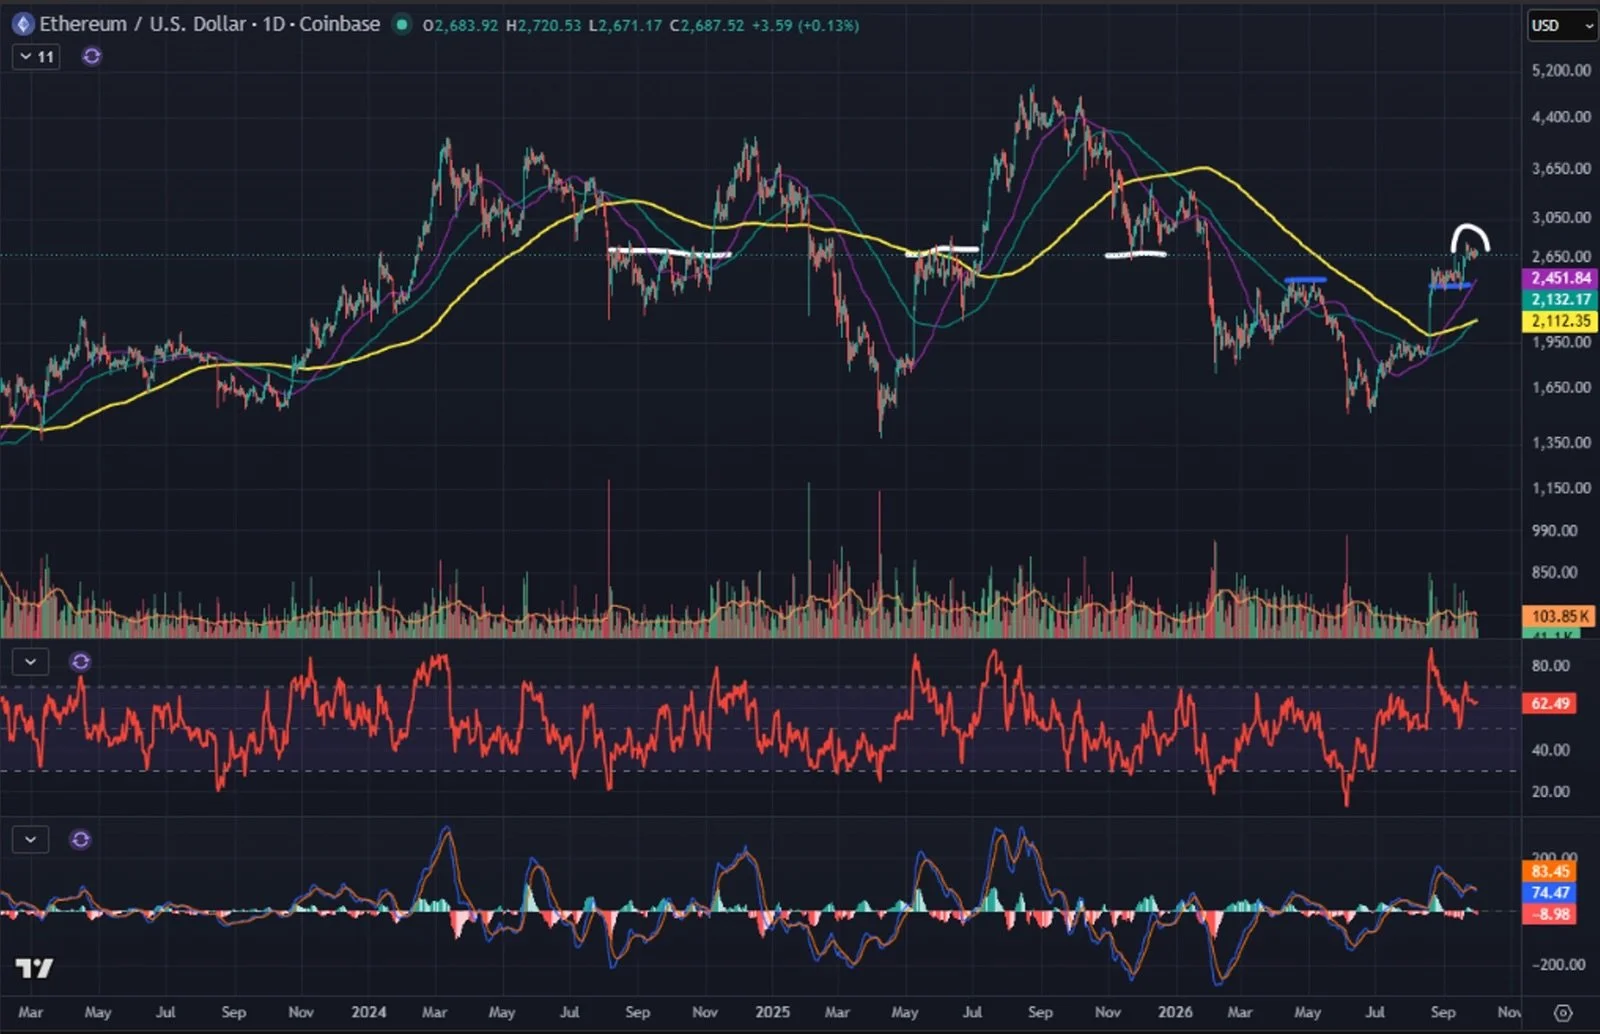
ETH is a somewhat different looking chart than BTC at the moment-
Source: TradingView. As of 10/1/26.
ETH actually got its higher high in August after the pump (blue), rode that S/R flip for weeks (like BTC is doing now) and then took a small leg higher and is now sitting at a significant S/R level going back two years (white).
I struggle to understand the upside from here on ETH (and most any other crypto for that matter). ETH is a $328bn market cap. ETH price could go down 75% and it would still be overvalued by any reasonable definition of that term.
In last month’s letter we spent a lot of time digging into the big crypto breakout on Aug 19th, trying to understand what happened there and why. At the end of that analysis, I said-
“But so far, I haven’t been able to bring myself to buy any. I haven’t been convinced by the follow-through so far. And as I’ve tried to explain here, I think the conditions under which the squeeze occurred in the first place are not necessarily still in place.”
Here we are a month later and prices are a bit higher and I still feel the same way. I think the move up crypto had in Sept was pretty weak overall. Not compelling enough to get me to buy. It would be different if I were sitting in a bunch of cash. But I’m not. The portfolio is pretty fully deployed, just into AIVC stocks rather than crypto. So for me, it’s been about assessing the risk-adjusted return opportunity in BTC/crypto vs AIVC. And I own no crypto. So that tells you how I’m feeling about that R/R at the moment.
Closing Remarks
Through the first three quarters of 2026, stocks are having a pretty fantastic year overall. Once you take into consideration the Iran conflict and its knock-on effects (higher oil, higher inflation, rate hike), the performance is even more impressive. SPX +12% YTD. QQQ +20%. SOXX +89%.
BTC and ETH are down 5 and 10% YTD, respectively. So that’s a fair amount of underperformance vs equities, but it’s also a big bounce from a couple months ago. At 6/30, BTC and ETH were down 34% and 48% YTD. So crypto clawed a lot back in Q3 – BTC and ETH were +43% and +71% Q3.
The strong SPX performance is pretty straightforward – the energy and tech sectors have carried the broader index. The explanations for each of those sectors’ strong YTD performances are also straightforward – Iran and AI.
The YTD crypto performance is trickier to explain, especially the magnitude of the Q3 bounce. Some amount of bounce certainly made sense, just coming off of deeply oversold levels. But the total size of the bounce is still a headscratcher for me relative to how I see the fundamentals of BTC and crypto broadly – which is to say, not that great and nothing particularly bright on the horizon.
Wish I saw it differently. If you see it differently, let me know why. Maybe I’m missing something.
“A stick before you fall.”
– Japanese Proverb
Travis Kling
Founder & Chief Investment Officer
Ikigai Asset Management
1. Ikigai Asset Management is the trade name for a collection of advisory and consulting businesses operated by Travis Kling, Anthony Emtman, and their team.
The information contained or attached herein is not intended to provide, and should not be relied upon for, accounting, legal or tax advice or investment recommendations. This presentation may contain forward-looking statements that are within the meaning of Section 27A of the Securities Act of 1933 and Section 21E of the Securities Exchange Act of 1934. These forward-looking statements are based on management’s beliefs, as well as assumptions made by, and information currently available to, management. Although management believes that the expectations reflected in these forward-looking statements are reasonable, it can give no assurance that these expectations will prove to be correct. This email is for informational purposes only and does not constitute an offer to sell, or the solicitation of an offer to buy, any security, product, service of Ikigai as well as any Ikigai fund, whether an existing or contemplated fund, for which an offer can be made only by such fund’s Confidential Private Placement Memorandum and in compliance with applicable law. Past performance is not indicative nor a guarantee of future returns. Please consult your own independent advisors. All information is intended only for the named recipient(s) above and is covered by the Electronic Communications Privacy Act 18 U.S.C. Section 2510-2521. This email is confidential and may contain information that is privileged or exempt from disclosure under applicable law. If you have received this message in error please immediately notify the sender by return email and delete this email message from your computer. Copyright 2023 Ikigai Asset Management, LLC. All Rights Reserved.
NOT INVESTMENT ADVICE; FOR INFORMATION ONLY
PAST PERFORMANCE IS NOT A GUARANTEE OF FUTURE RESULTS
